SBI Home Loan EMI Goes Up: EBLR Now 8.15% — Here’s How Much More You Pay
SBI has raised its EBLR to 8.15%, RLLR to 7.75% and MCLR by up to 0.15% from 15 October 2026. See the new rates and how much more you will pay on a home loan EMI.
On this page 7 sections
State Bank of India has raised its key lending rates from 15 October 2026, a week after the RBI hiked the repo rate by 0.25% to 5.50%. The external benchmark lending rate (EBLR) is now 8.15%, up from 7.90%, and the repo-linked lending rate (RLLR) is 7.75%, up from 7.50%. MCLR has risen by 0.15% on 3-month to 1-year tenors. If you have an SBI home loan, your EMI or tenure will go up at your next reset. Here are the new rates and what they mean for you.
Quick answer: SBI EBLR: 7.90% → 8.15%. RLLR: 7.50% → 7.75%. 1-year MCLR: 8.70% → 8.85%. A 0.25% rise adds about ₹635 a month to a 20-year ₹40 lakh home loan.
Key takeaways
- SBI raised EBLR and RLLR by the full 0.25% repo hike, effective 15 October 2026.
- MCLR went up 0.15% on 3-month, 6-month and 1-year tenors; overnight and 1-month MCLR are unchanged at 7.85%.
- Most home loans taken after October 2019 are linked to EBLR, so they will reprice at the next reset date.
- Ask the bank to raise your EMI rather than extend the tenure: on a ₹50 lakh loan, extending costs about ₹3.5 lakh more.
- SBI has not raised FD rates, so the gap between what you pay and what you earn has widened.
SBI’s new lending rates
| Benchmark | Old rate | New rate (from 15 Oct 2026) | Change |
|---|---|---|---|
| EBLR | 7.90% | 8.15% | +0.25% |
| RLLR | 7.50% | 7.75% | +0.25% |
| MCLR – overnight & 1 month | 7.85% | 7.85% | No change |
| MCLR – 3 months | 8.25% | 8.40% | +0.15% |
| MCLR – 6 months | 8.60% | 8.75% | +0.15% |
| MCLR – 1 year | 8.70% | 8.85% | +0.15% |
Your actual home loan rate is the benchmark plus a spread that depends mainly on your CIBIL score. So if your loan was at EBLR + 0.40%, it moves from 8.30% to 8.55%. A higher score gets a lower spread, which is one more reason to improve your CIBIL score before you borrow.
How much will your EMI go up?
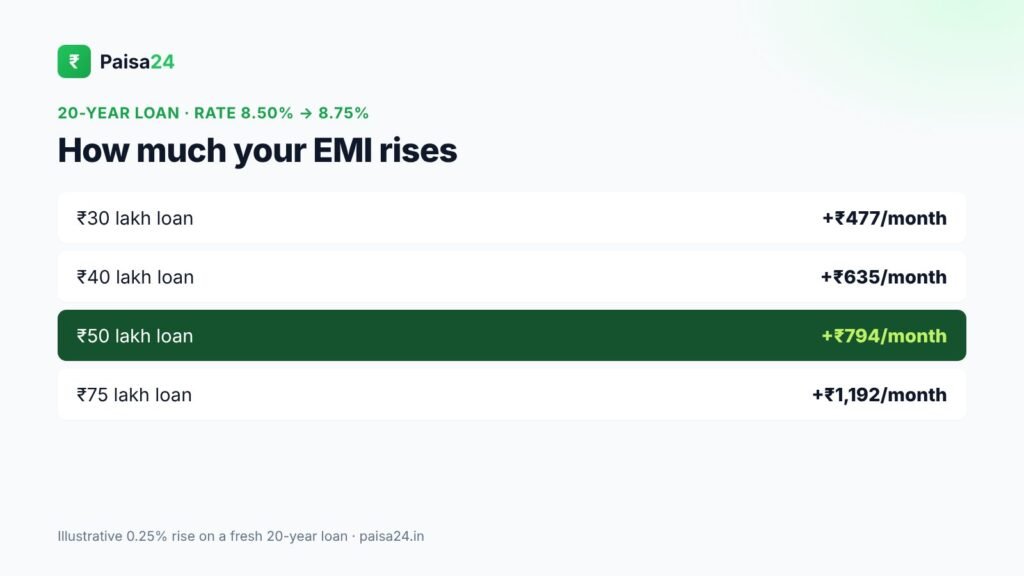
| Loan amount (20 years) | EMI at 8.50% | EMI at 8.75% | Extra per month | Extra over 20 years |
|---|---|---|---|---|
| ₹30 lakh | ₹26,035 | ₹26,511 | ₹477 | ₹1.14 lakh |
| ₹40 lakh | ₹34,713 | ₹35,348 | ₹635 | ₹1.53 lakh |
| ₹50 lakh | ₹43,391 | ₹44,186 | ₹794 | ₹1.91 lakh |
| ₹75 lakh | ₹65,087 | ₹66,278 | ₹1,192 | ₹2.86 lakh |
See the full tables for your loan size: ₹30 lakh, ₹40 lakh and ₹50 lakh home loan EMI.
Free calculatorRecalculate your EMI at the new rateHome, car & personal loan EMI with a full schedule.Higher EMI or longer tenure? Choose the EMI
When rates rise, banks usually keep your EMI the same and quietly extend the tenure. That feels painless but costs more. Take a ₹50 lakh, 20-year loan whose rate goes from 8.50% to 8.75%:
| Option | What happens | Extra cost |
|---|---|---|
| Raise the EMI | EMI goes up ₹794; loan ends on time | about ₹1.9 lakh |
| Keep EMI, extend tenure | About 12 extra EMIs at the end | about ₹5.4 lakh |
Write to your branch or use the bank’s app to opt for a higher EMI. If you can, add a small prepayment each year as well; floating-rate home loans have no prepayment penalty.
Which loans are affected?
- EBLR/RLLR-linked loans (most home loans since October 2019): rate changes at your next reset, usually every three months.
- MCLR-linked loans: change at your reset date, often once a year, by 0.15% if on 1-year MCLR.
- Old base-rate loans: not directly affected, but these are usually more expensive; consider switching to EBLR.
- Fixed-rate personal and car loans: no change for existing borrowers; new loans may cost more.
Will other banks follow?
Yes. Since more than half of bank loans are linked to external benchmarks, most banks pass on repo changes within weeks. Expect similar 0.25% increases on repo-linked home loans across public and private banks. On the deposit side, only a few banks, such as ICICI Bank and Indian Bank, have raised rates so far; see FD rates after the repo hike.
Frequently asked questions
What is SBI’s EBLR from 15 October 2026?
8.15%, up from 7.90%. The RLLR is 7.75%.
What is SBI’s 1-year MCLR now?
8.85%, up 0.15% from 8.70%, effective 15 October 2026.
Will my SBI home loan EMI increase?
If your loan is linked to EBLR or RLLR, the rate rises by 0.25% at your next reset. SBI may extend your tenure instead of raising the EMI unless you ask for a higher EMI.
How much will my EMI rise on a ₹50 lakh home loan?
About ₹794 a month on a 20-year loan going from 8.50% to 8.75%.
Should I switch my home loan to another bank?
Only if the rate gap is at least 0.5% and you have many years left. Factor in processing, legal and valuation fees.
Related guides and calculators
- EMI for ₹40 lakh home loan
- EMI for ₹50 lakh home loan
- FD rates after the RBI repo hike
- Prepay home loan: reduce EMI or tenure?
- EMI calculator
Sources: SBI · RBI. Last checked 30 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.