How to Improve CIBIL Score Fast: 7 Proven Steps (2026)
How to improve CIBIL score fast: 7 proven steps, how long it takes, fixing errors in your credit report and myths that hold your score back.
On this page 7 sections
A good credit score gets you loans faster and at lower interest. So if yours is low, here is the good news: you can improve your CIBIL score in a few months with a handful of habits. This guide explains what the score measures, the fastest legal ways to raise it, how long it really takes, and how to fix errors in your report.
Key takeaways
- CIBIL scores run from 300 to 900; most lenders prefer 750 or more.
- Paying on time and keeping card use below 30% of your limit matter most.
- Lenders now report to credit bureaus every 15 days, so good habits show up faster.
- You can get a free full credit report from each bureau once a year and dispute errors.
What is a CIBIL score?
Your CIBIL score is a three-digit number from 300 to 900 that sums up how you have handled credit. TransUnion CIBIL is the best-known bureau, and Experian, Equifax and CRIF High Mark also give scores. In general, banks treat the ranges like this:
| Score | What it means (and whether you need to improve CIBIL score) |
|---|---|
| 750–900 | Excellent: best rates, quick approvals |
| 700–749 | Good: approvals likely, rates may be a little higher |
| 650–699 | Fair: limited options, higher rates |
| 300–649 | Poor: many applications get rejected |
| NH or -1 | No history yet; normal for first-time borrowers |
How to improve CIBIL score: 7 proven steps
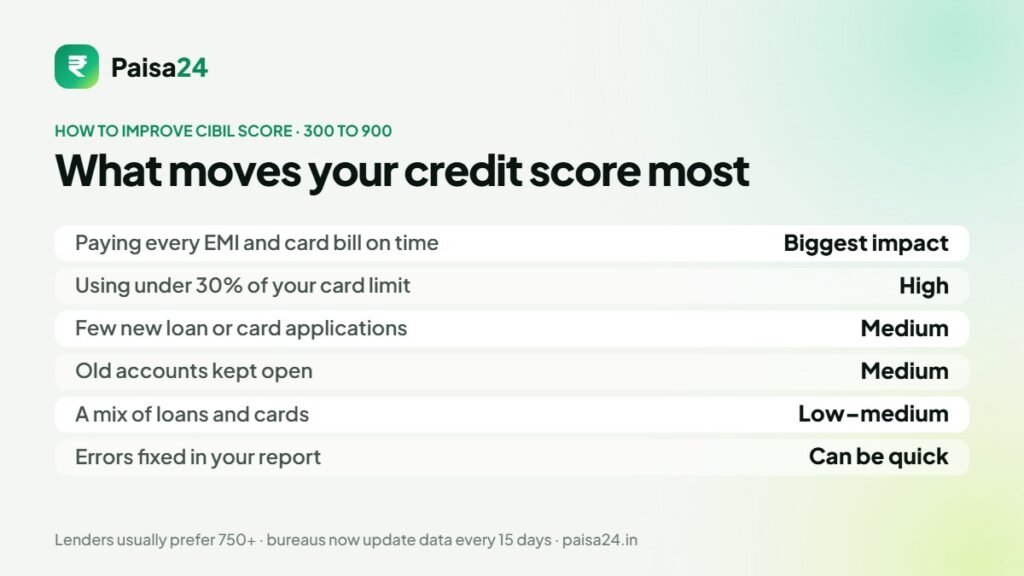
- Pay every EMI and card bill on time. Payment history is the biggest factor. Even one payment 30 days late can drop your score sharply, so set up auto-debit.
- Keep credit card use under 30%. If your limit is ₹1 lakh, try to keep the statement balance below ₹30,000. Paying part of the bill before the statement date also helps.
- Clear overdue amounts first. Old overdue accounts hurt the most, so clearing them is the first way to improve CIBIL score. Pay them off and get a “no dues” letter.
- Avoid many applications at once. Each loan or card application creates a hard enquiry. Instead, space them out by a few months.
- Keep old cards open. A long credit history helps. So unless a card has a high annual fee, keep your oldest one active with small spends.
- Build a healthy mix. A combination of a card and a secured loan, like a home or gold loan, shows you can handle different credit.
- Check your report for errors and dispute them (see below).
Quick win: Ask your card issuer for a higher credit limit while keeping your spending the same. As a result, your utilisation drops instantly, a quick way to improve CIBIL score,, which can lift your score within one or two billing cycles.
How long does it take to improve CIBIL score?
It depends on where you start. Under RBI rules, lenders now send updates to credit bureaus every 15 days, so changes show up faster than before. Still, trust takes time to build:
| Starting situation (to improve CIBIL score) | Typical time to see a clear rise |
|---|---|
| High card usage, otherwise clean | 1–3 months |
| A few late payments | 6–12 months of clean payments |
| Defaults or settled accounts | 12–24 months or more |
| No credit history | 6–12 months after your first card or loan |
Fix errors in your credit report
Errors can quietly block any effort to improve CIBIL score. In fact, mistakes are more common than you think: a loan you closed may still show as active, or someone else’s account may appear in your report. Therefore, check your report at least once a year.
- Download your free annual report from each bureau.
- Look for wrong personal details, accounts you never opened, or closed loans shown as open.
- Raise a dispute on the bureau’s website with proof, such as a no-dues certificate.
- Follow up with the lender too, because the bureau corrects data based on what the lender confirms.
Bureaus must resolve complaints within a set time, and RBI rules require them to pay compensation for delays. So do not ignore an error; it can cost you a loan.
Myths that stop people from improving their CIBIL score
- “Checking my own score lowers it.” No. Your own checks are soft enquiries and have no effect.
- “Closing all cards helps.” Actually, it can lower your score by cutting your available credit and history.
- “Settling a loan is as good as closing it.” No. A “settled” status hurts your score for years; full repayment is far better.
- “Income affects my score.” It does not. Your score reflects repayment behaviour, not salary.
A credit card can help you improve CIBIL score
Used well, a credit card is the easiest way to improve CIBIL score over time. For example, small monthly spends paid in full on time create a steady record of good behaviour. If you have no history, start with a secured card against an FD. Read our guide on choosing your first credit card.
Free calculatorPlan an EMI you can always pay on timeHome, car & personal loan EMI with a full schedule.Frequently asked questions
How can I improve my CIBIL score quickly?
To improve CIBIL score quickly, pay all dues on time, bring card usage below 30% of your limit, clear any overdue amounts and fix errors in your report. Usage changes can show within one or two months.
What is a good CIBIL score in India?
750 or above is considered good by most lenders and gets the best loan rates.
Does checking my CIBIL score reduce it?
No. Checking your own score is a soft enquiry and has no impact.
How often is my CIBIL score updated?
Lenders now report data to bureaus every 15 days, so your score can change about twice a month.
Can I improve my CIBIL score after a loan settlement?
Yes, slowly. Keep all other accounts clean for 12–24 months and, if possible, pay the settled loan’s balance in full and ask the lender to update the status to closed.
Sources: Reserve Bank of India · TransUnion CIBIL. Last checked 21 October 2026. Figures are estimates for guidance, not tax or financial advice.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.