₹5 Lakh Personal Loan EMI for 1 to 5 Years (2026 Table)
The EMI for a ₹5 lakh personal loan is about ₹16,847 a month for 3 years at 13%. See EMIs for 1 to 5 years at 11% to 18%.
On this page 12 sections
- 01EMI for ₹5 lakh personal loan: full table
- 02Total interest on ₹5 lakh
- 03Where your EMI goes: principal vs interest
- 04The real cost: processing fee and APR
- 05What decides your interest rate?
- 06Salary needed for a ₹5 lakh personal loan
- 07Prepaying a personal loan: does it save money?
- 08Cheaper alternatives to a personal loan
- 09How to get a cheaper personal loan
- 10Documents you usually need
- 11Frequently asked questions
- 12Related guides and calculators
The EMI for a ₹5 lakh personal loan is about ₹16,847 a month for 3 years at 13% interest. Over 5 years it drops to about ₹11,377, but you pay much more interest. Below are EMIs for every tenure from 1 to 5 years at rates from 10.5% to 24%, the true cost after fees, the salary you need, and cheaper ways to borrow.
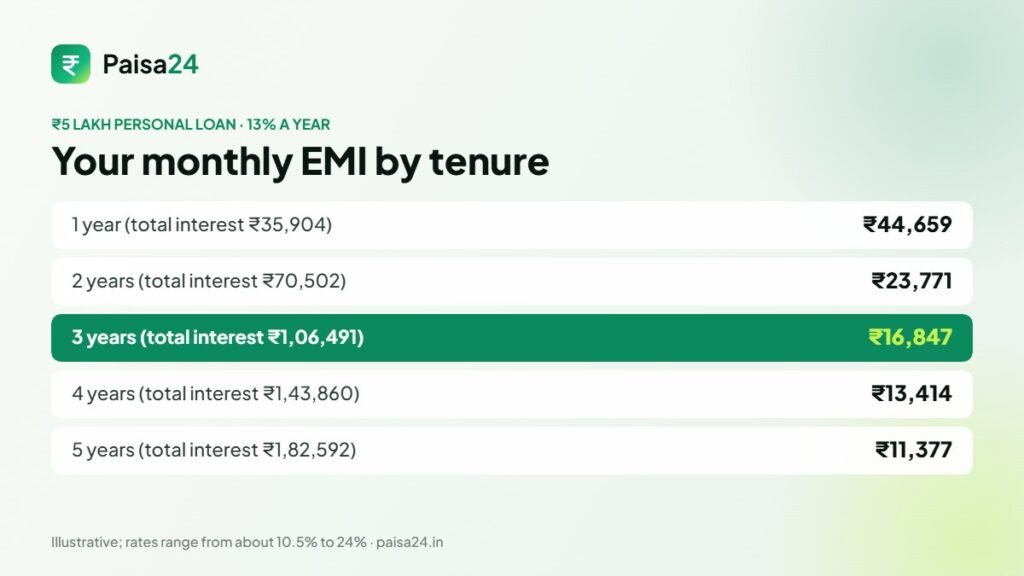
Quick answer: ₹5 lakh personal loan EMI at 13%: ₹44,659 (1 year), ₹23,771 (2 years), ₹16,847 (3 years), ₹13,414 (4 years) and ₹11,377 (5 years).
Key takeaways
- ₹5 lakh for 3 years at 13%: EMI about ₹16,847, total interest about ₹1,06,491.
- Personal loan rates usually range from about 10.5% to 24%, depending on your credit score, income and employer.
- Processing fees of 1% to 3% plus 18% GST raise the real cost: a 13% loan with a 2% fee costs about 14.7% a year.
- A loan against an FD, a gold loan or a home loan top-up is usually much cheaper.
EMI for ₹5 lakh personal loan: full table
| Tenure | 11% | 13% | 15% | 18% |
|---|---|---|---|---|
| 1 year | ₹44,191 | ₹44,659 | ₹45,129 | ₹45,840 |
| 2 years | ₹23,304 | ₹23,771 | ₹24,243 | ₹24,962 |
| 3 years | ₹16,369 | ₹16,847 | ₹17,333 | ₹18,076 |
| 4 years | ₹12,923 | ₹13,414 | ₹13,915 | ₹14,687 |
| 5 years | ₹10,871 | ₹11,377 | ₹11,895 | ₹12,697 |
EMI at other interest rates
| Interest rate | 1 year | 2 years | 3 years | 4 years | 5 years |
|---|---|---|---|---|---|
| 10.5% | ₹44,074 | ₹23,188 | ₹16,251 | ₹12,802 | ₹10,747 |
| 12% | ₹44,424 | ₹23,537 | ₹16,607 | ₹13,167 | ₹11,122 |
| 14% | ₹44,894 | ₹24,006 | ₹17,089 | ₹13,663 | ₹11,634 |
| 16% | ₹45,365 | ₹24,482 | ₹17,579 | ₹14,170 | ₹12,159 |
| 20% | ₹46,317 | ₹25,448 | ₹18,582 | ₹15,215 | ₹13,247 |
| 24% | ₹47,280 | ₹26,436 | ₹19,616 | ₹16,301 | ₹14,384 |
Total interest on ₹5 lakh
| Tenure | EMI at 13% | Total interest | Total paid |
|---|---|---|---|
| 1 year | ₹44,659 | ₹35,904 | ₹5,35,904 |
| 2 years | ₹23,771 | ₹70,502 | ₹5,70,502 |
| 3 years | ₹16,847 | ₹1,06,491 | ₹6,06,491 |
| 4 years | ₹13,414 | ₹1,43,860 | ₹6,43,860 |
| 5 years | ₹11,377 | ₹1,82,592 | ₹6,82,592 |
Stretching the loan from 3 to 5 years lowers the EMI by about ₹5,470, but adds about ₹76,000 of interest. Choose the shortest tenure whose EMI you can pay comfortably every month.
Where your EMI goes: principal vs interest
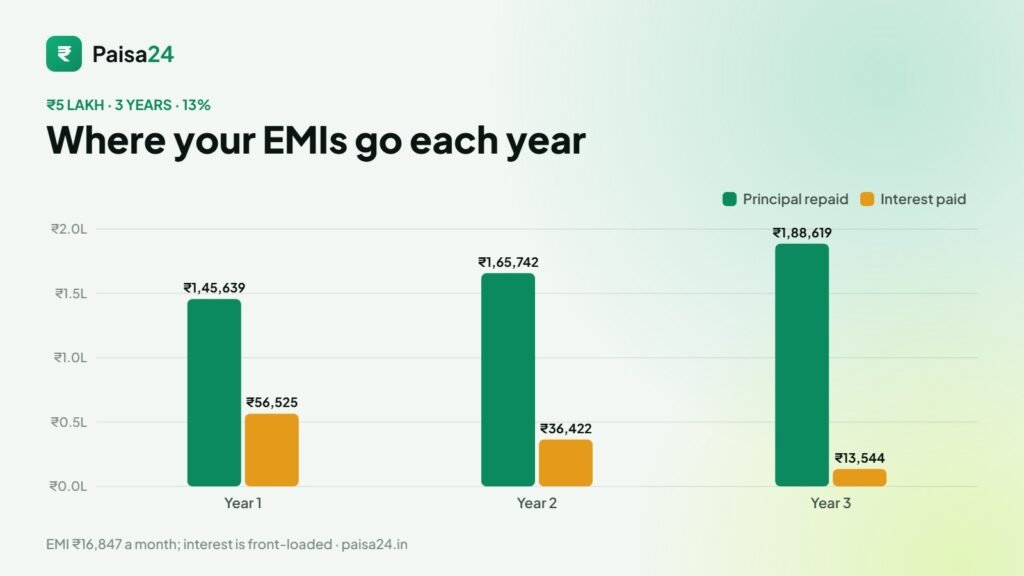
| Year | Principal repaid | Interest paid | Balance at year-end |
|---|---|---|---|
| Year 1 | ₹1,45,639 | ₹56,525 | ₹3,54,361 |
| Year 2 | ₹1,65,742 | ₹36,422 | ₹1,88,619 |
| Year 3 | ₹1,88,619 | ₹13,544 | ₹0 |
Because interest is front-loaded, prepaying early saves the most. More on that below.
The real cost: processing fee and APR
Lenders advertise the interest rate, but you also pay a processing fee, usually 1% to 3% of the loan, plus 18% GST on the fee. The fee is often deducted from the amount you receive.
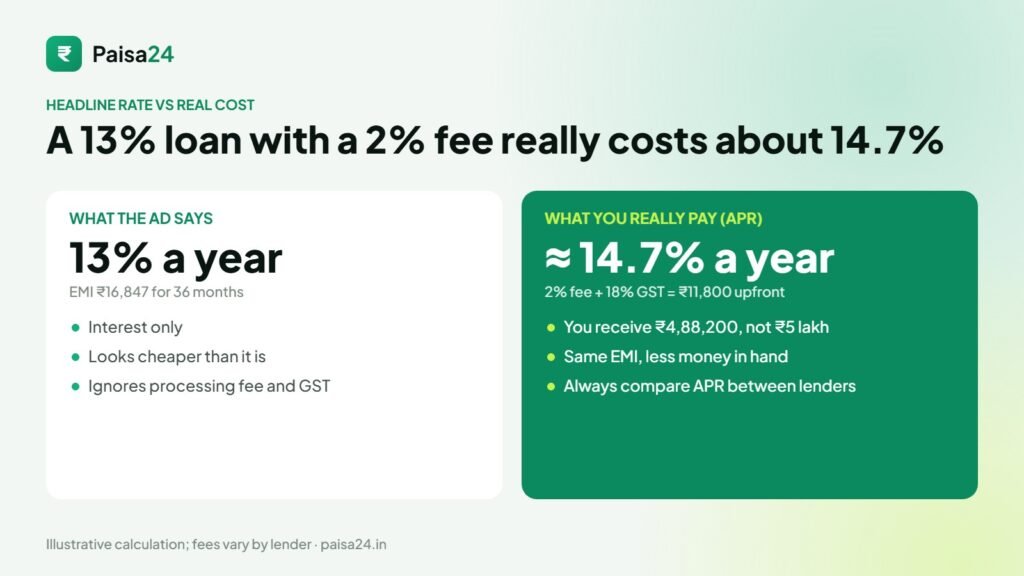
Example: on ₹5 lakh at 13% for 3 years with a 2% fee, you pay ₹10,000 plus ₹1,800 GST, so you receive ₹4,88,200 but still repay ₹16,847 a month on the full ₹5 lakh. That takes your effective annual cost (APR) to about 14.7%. RBI rules require lenders to show you a Key Fact Statement with the APR before you sign, so ask for it.
Watch out for add-ons: Some lenders bundle loan insurance or other products into the loan. These are optional, raise your cost, and you can ask for them to be removed.
What decides your interest rate?
- Credit score: a CIBIL score above 750 usually gets the lowest rates. Below 700, rates rise sharply or applications get rejected. See how to improve your CIBIL score.
- Income and employer: employees of large, well-known companies and government staff often get lower rates.
- Existing EMIs: if your current EMIs already take a big share of income, lenders charge more or approve less.
- Relationship with the bank: salary-account holders often get pre-approved offers at better rates.
- Loan amount and tenure: very small or very long loans can carry higher rates.
Salary needed for a ₹5 lakh personal loan
Lenders usually want all your EMIs to stay within 40% to 50% of your take-home pay. If you have no other loans:
| Tenure (13%) | EMI | Take-home needed at 50% limit | Take-home needed at 40% limit |
|---|---|---|---|
| 2 years | ₹23,771 | ₹47,542 | ₹59,428 |
| 3 years | ₹16,847 | ₹33,694 | ₹42,118 |
| 5 years | ₹11,377 | ₹22,754 | ₹28,443 |
If you already pay other EMIs, subtract them first. For example, with a ₹10,000 car loan EMI, a 3-year ₹5 lakh loan would need take-home pay of about ₹53,700 at the 50% limit.
Prepaying a personal loan: does it save money?
Usually yes, even after a fee. Say you prepay ₹1 lakh after 12 EMIs on a 3-year, 13% loan and keep the same EMI:
| No prepayment | Prepay ₹1 lakh after 12 EMIs | |
|---|---|---|
| Remaining EMIs | 24 | 17 |
| Interest still to pay | ₹49,966 | ₹24,915 |
| Prepayment fee (3% + GST) | ₹0 | ₹3,540 |
| Net saving | about ₹21,500 |
Most personal loans are fixed-rate, so lenders can charge a prepayment or foreclosure fee, often 2% to 5%, and many allow it only after 6 to 12 EMIs. RBI rules do not allow prepayment charges on floating-rate loans to individuals for non-business use, so check whether your loan is fixed or floating in the loan agreement.
Cheaper alternatives to a personal loan
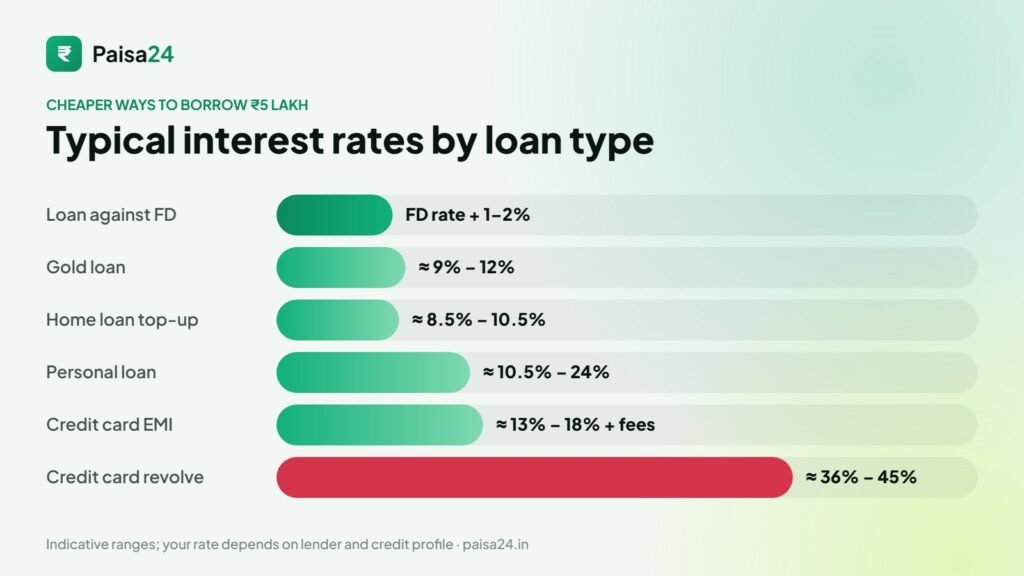
| Option | Typical rate | Best for |
|---|---|---|
| Loan or overdraft against FD | FD rate + 1% to 2% | You have FDs you do not want to break |
| Gold loan | About 9% to 12% | Short-term needs, quick cash |
| Home loan top-up | About 8.5% to 10.5% | Existing home loan borrowers |
| Loan against PPF | 1% above PPF rate | Years 3 to 6 of a PPF account |
| Personal loan | About 10.5% to 24% | No assets to pledge |
| Credit card revolving | About 36% to 45% a year | Avoid |
How to get a cheaper personal loan
- Check pre-approved offers from your salary bank first; they are often the cheapest and fastest.
- Improve your CIBIL score before applying: pay all dues on time and keep card use below 30%.
- Compare APR (rate plus fees) across at least three lenders, not just the headline rate.
- Apply to one lender at a time. Many applications in a short period create hard enquiries and lower your score.
- Borrow only what you need and choose the shortest tenure you can comfortably afford.
Documents you usually need
- PAN card and Aadhaar (or other address proof)
- Last 3 months’ salary slips
- Last 6 months’ bank statements showing salary credits
- Form 16 or ITR, especially for self-employed applicants
Before you borrow: If you have an FD or PPF balance, a loan against it is usually much cheaper than a personal loan, and you keep earning interest on the deposit.
How we calculated this: EMIs use the standard reducing-balance formula: EMI = P × r × (1+r)^n ÷ ((1+r)^n − 1), where r is the monthly rate and n is the number of months. APR is the rate at which the amount actually received equals the present value of all EMIs. Rates for alternatives are indicative ranges, not offers.
Frequently asked questions
What is the EMI for a ₹5 lakh loan for 5 years?
About ₹11,377 a month at 13%, ₹10,871 at 11% and ₹12,697 at 18%.
What is the EMI for ₹5 lakh for 3 years?
About ₹16,847 a month at 13%, or ₹16,607 at 12%.
What is the EMI for ₹5 lakh for 2 years?
About ₹23,771 a month at 13%.
What salary do I need for a ₹5 lakh personal loan?
For a 3-year loan at 13%, a take-home of roughly ₹34,000 to ₹42,000 a month if you have no other EMIs.
Is a 13% personal loan rate good?
It is around the middle of the market. Borrowers with high credit scores and strong employers can get 10.5% to 12%, while others pay 16% or more.
Does a personal loan affect my credit score?
Each application creates a hard enquiry, which can lower your score slightly. Paying every EMI on time improves your score over time.
Can I prepay a personal loan?
Usually yes, often after 6 to 12 EMIs. Fixed-rate personal loans may carry a prepayment fee of 2% to 5% plus GST, so read your loan agreement.
What is cheaper than a personal loan?
A loan against an FD, a gold loan or a top-up on an existing home loan usually costs much less.
Related guides and calculators
- How to improve your CIBIL score fast
- EMI for ₹30 lakh home loan
- EMI calculator
- How to choose your first credit card
Sources: Reserve Bank of India · RBI Key Fact Statement directions · TransUnion CIBIL. Last checked 24 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.