EMI for ₹30 Lakh Home Loan: 10, 15, 20, 25 & 30 Years (2026)
The EMI for a ₹30 lakh home loan is about ₹25,093 a month for 20 years at 8%. See EMI tables for 10 to 30 years at 7.5% to 9%.
On this page 11 sections
- 01EMI for ₹30 lakh home loan: full table
- 02Total interest you pay on ₹30 lakh
- 03Why the balance falls so slowly
- 04What salary do you need for a ₹30 lakh home loan?
- 05How much down payment do you need?
- 06How a repo rate hike affects your EMI
- 07Tax benefits on a ₹30 lakh home loan
- 08How to pay much less interest
- 09How to get a lower EMI
- 10Frequently asked questions
- 11Related guides and calculators
The EMI for a ₹30 lakh home loan is about ₹25,093 a month for 20 years at 8% interest. Choose 30 years and the EMI falls to ₹22,013, but you pay about ₹49 lakh in interest, more than the loan itself. Below are EMI tables for every common tenure and rate in October 2026, the salary you need, the down payment, tax benefits and how to cut your interest.
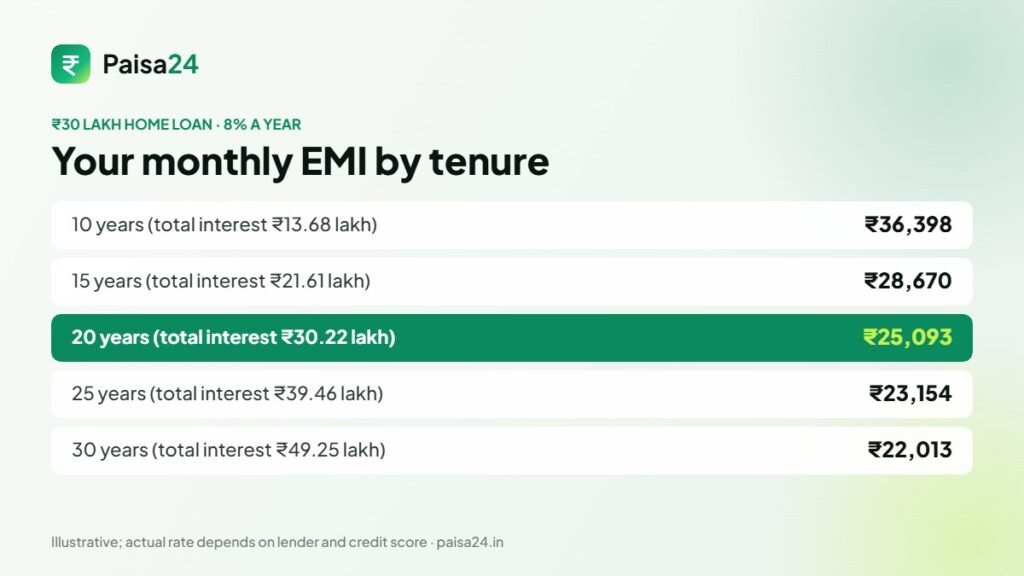
Quick answer: ₹30 lakh home loan EMI at 8%: ₹36,398 (10 years), ₹28,670 (15 years), ₹25,093 (20 years), ₹23,154 (25 years) and ₹22,013 (30 years).
Key takeaways
- ₹30 lakh for 20 years at 8%: EMI about ₹25,093, total interest about ₹30.22 lakh.
- Home loan rates start around 7.5% after the October 2026 repo rate hike to 5.50%, and most borrowers pay 7.5% to 9%.
- Raising your EMI by just 5% a year saves about ₹10.6 lakh and ends the loan almost 8 years early.
- Banks usually want your total EMIs to stay under 50% of take-home pay, so a 20-year loan needs about ₹50,000 a month.
EMI for ₹30 lakh home loan: full table
| Tenure | 7.5% | 8% | 8.5% | 9% |
|---|---|---|---|---|
| 10 years | ₹35,611 | ₹36,398 | ₹37,196 | ₹38,003 |
| 15 years | ₹27,810 | ₹28,670 | ₹29,542 | ₹30,428 |
| 20 years | ₹24,168 | ₹25,093 | ₹26,035 | ₹26,992 |
| 25 years | ₹22,170 | ₹23,154 | ₹24,157 | ₹25,176 |
| 30 years | ₹20,976 | ₹22,013 | ₹23,067 | ₹24,139 |
EMI at higher rates
If your credit score is lower, or you borrow from a housing finance company, you may pay more. Here are EMIs at 9.5% and 10%:
| Tenure | 9.5% | 10% |
|---|---|---|
| 10 years | ₹38,819 | ₹39,645 |
| 15 years | ₹31,327 | ₹32,238 |
| 20 years | ₹27,964 | ₹28,951 |
| 25 years | ₹26,211 | ₹27,261 |
| 30 years | ₹25,226 | ₹26,327 |
Total interest you pay on ₹30 lakh
The longer the tenure, the more interest you pay over the life of the loan. At 8%:
| Tenure | Monthly EMI | Total interest | Total paid |
|---|---|---|---|
| 10 years | ₹36,398 | ₹13.68 lakh | ₹43.68 lakh |
| 15 years | ₹28,670 | ₹21.61 lakh | ₹51.61 lakh |
| 20 years | ₹25,093 | ₹30.22 lakh | ₹60.22 lakh |
| 25 years | ₹23,154 | ₹39.46 lakh | ₹69.46 lakh |
| 30 years | ₹22,013 | ₹49.25 lakh | ₹79.25 lakh |
Going from 20 to 30 years cuts your EMI by only about ₹3,080, but adds about ₹19 lakh of interest. A common middle path is to take a longer tenure for safety and then prepay whenever you can.
Why the balance falls so slowly
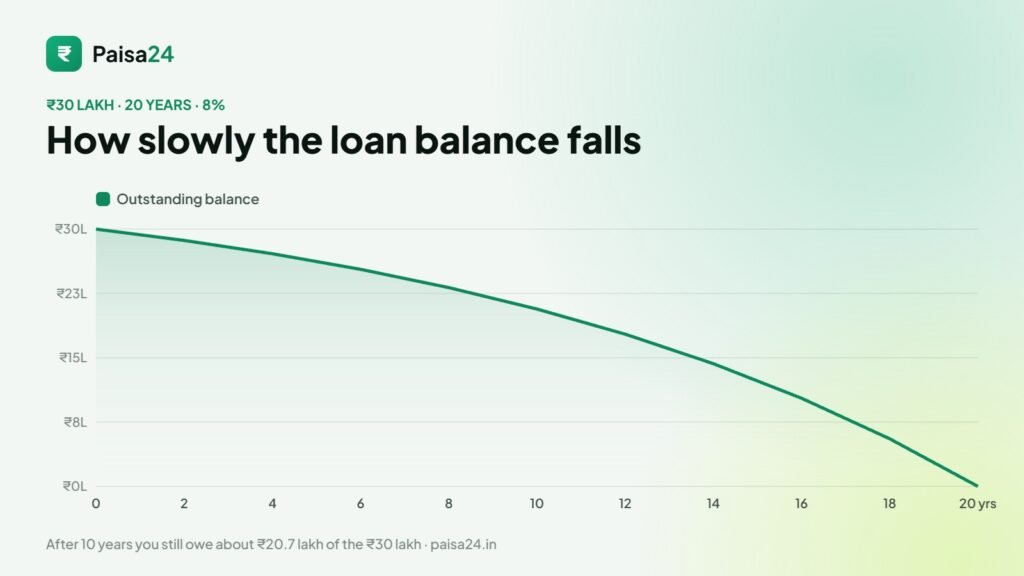
In the first year of a 20-year, 8% loan, you pay about ₹2.38 lakh of interest and only about ₹63,400 of principal. Even after 10 years of EMIs, about ₹20.7 lakh is still outstanding. That is why prepayments made in the first 5 to 7 years save the most interest. Read our detailed guide on whether to reduce EMI or tenure when you prepay.
What salary do you need for a ₹30 lakh home loan?
Most banks allow total EMIs of up to about 50% of your net monthly income, and some cap it lower for smaller incomes. With no other loans, at 8%:
| Tenure | EMI | Minimum take-home (50% rule) |
|---|---|---|
| 10 years | ₹36,398 | About ₹72,800 |
| 15 years | ₹28,670 | About ₹57,300 |
| 20 years | ₹25,093 | About ₹50,200 |
| 25 years | ₹23,154 | About ₹46,300 |
| 30 years | ₹22,013 | About ₹44,000 |
Lenders also look at your age (the loan usually has to end by 60 to 70), job stability and credit score. See your own number with the eligibility calculator below, or check our CTC vs in-hand salary guide to find your real take-home.
Free calculatorCheck how big a home loan your salary getsHow big a home loan your salary can get you.How much down payment do you need?
RBI limits how much of a property’s value a bank can lend (the loan-to-value or LTV ratio). For loans up to ₹30 lakh, banks can lend up to 90% of the property value. So for a ₹30 lakh loan:
- The property should be worth at least about ₹33.3 lakh.
- You pay at least 10% (about ₹3.3 lakh) yourself, plus stamp duty and registration, which are typically 5% to 8% of the property value depending on the state and are not funded by the loan.
- Many banks prefer to lend 75% to 80%, so plan for a bigger down payment if you can. Every ₹1 lakh less borrowed cuts the EMI by about ₹836 (20 years, 8%).
How a repo rate hike affects your EMI
Most new home loans are linked to the RBI repo rate. When the RBI raised the repo rate by 0.25% to 5.50% in October 2026, banks began passing the increase on to floating-rate borrowers at their next reset date.
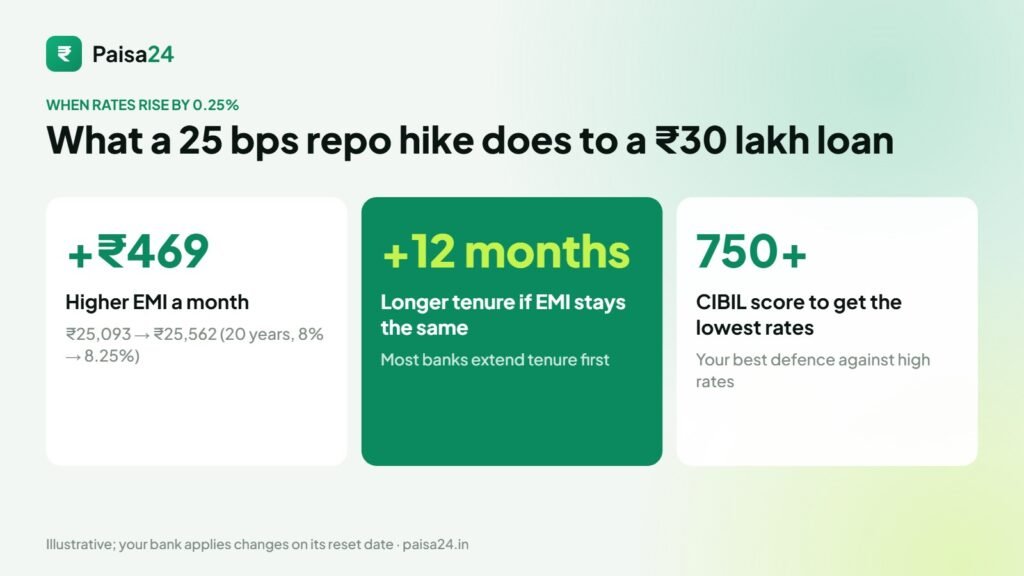
On a fresh ₹30 lakh, 20-year loan, a rise from 8% to 8.25% adds about ₹469 to the EMI, or about 12 months to the tenure if your bank keeps the EMI unchanged. Banks usually extend the tenure first. If yours does, consider increasing the EMI yourself, so the loan does not stretch for years.
Tax benefits on a ₹30 lakh home loan
| Benefit | Old regime | New regime |
|---|---|---|
| Interest on a self-occupied home | Up to ₹2 lakh a year | Not allowed |
| Principal repayment (80C, now Section 123) | Within the ₹1.5 lakh limit | Not allowed |
| Interest on a let-out home | Deductible against rent; loss set-off capped at ₹2 lakh | Deductible against rent; no loss set-off |
In year 1 of a 20-year, 8% loan, your interest is about ₹2.38 lakh, so you can use the full ₹2 lakh deduction in the old regime. Combined with HRA and 80C, a home loan is often what tips the balance towards the old regime.
How to pay much less interest
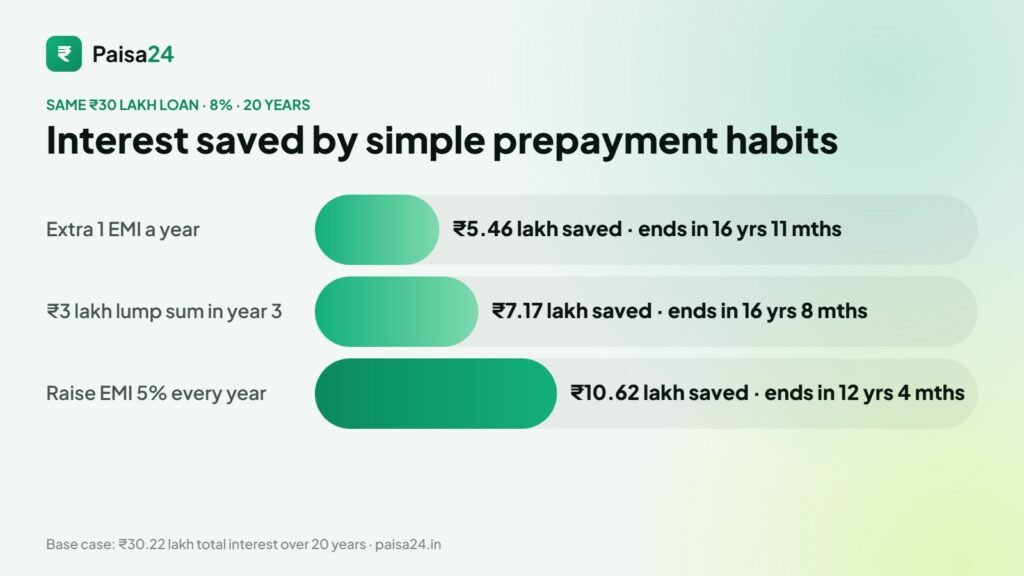
| Strategy | Loan ends in | Interest saved |
|---|---|---|
| No prepayment | 20 years | — |
| One extra EMI every year | 16 years 11 months | About ₹5.46 lakh |
| ₹3 lakh lump sum after 3 years | 16 years 8 months | About ₹7.17 lakh |
| Raise EMI by 5% every year | 12 years 4 months | About ₹10.62 lakh |
Under RBI directions effective 1 January 2026, banks cannot charge a prepayment penalty on floating-rate home loans taken by individuals, so prepay freely.
How to get a lower EMI
- Keep your CIBIL score above 750: it usually gets you the lowest rate. Read how to improve your CIBIL score.
- Make a bigger down payment to borrow less.
- Compare at least three lenders, including the processing fee (often up to 0.5% of the loan), not just the rate.
- Add a co-applicant; many banks give women borrowers a small rate concession.
- Ask for a rate reset if your loan is on an older benchmark such as MCLR or base rate, or consider a balance transfer if the gap is above 0.5%.
Tip: A 0.5% lower rate on ₹30 lakh for 20 years saves you about ₹2.26 lakh in interest. Negotiating the rate is worth the effort.
How we calculated this: EMIs use the standard reducing-balance formula with monthly rests. Prepayment scenarios keep the EMI unchanged and apply extra payments at the end of each loan year. Rates are indicative; your bank’s offer depends on its benchmark, your profile and the loan amount.
Frequently asked questions
What is the EMI for a ₹30 lakh home loan for 20 years?
About ₹25,093 a month at 8%, ₹24,168 at 7.5% and ₹26,992 at 9%.
What is the EMI for ₹30 lakh for 30 years?
About ₹22,013 a month at 8%. It is the lowest EMI, but total interest is about ₹49.25 lakh.
What is the EMI for ₹30 lakh for 15 years?
About ₹28,670 a month at 8%.
What salary is needed for a ₹30 lakh home loan?
At 8% for 20 years, a take-home of about ₹50,000 a month if you have no other EMIs. A shorter tenure needs more.
How much down payment is needed for a ₹30 lakh loan?
At least 10% of the property value, so about ₹3.3 lakh on a ₹33.3 lakh home, plus stamp duty and registration.
Can I get tax benefits on a home loan?
In the old regime, you can claim up to ₹2 lakh a year on interest for a self-occupied home and principal within the ₹1.5 lakh 80C limit. The new regime does not allow these for a self-occupied home.
Is it better to choose a shorter or longer tenure?
A longer tenure keeps the EMI affordable; a shorter one saves a lot of interest. Many people take a longer tenure and prepay whenever they can.
Will my EMI go up after the October 2026 repo hike?
If your loan is linked to the repo rate, your bank will raise the rate at its next reset. It may increase the EMI or extend the tenure. Ask your bank which it applies.
Related guides and calculators
- Home loan prepayment: reduce EMI or tenure?
- Home loan eligibility calculator
- EMI calculator
- ₹5 lakh personal loan EMI
- New vs old tax regime
Sources: Reserve Bank of India · RBI repo rate hike to 5.50% (SCC Online, 9 Oct 2026) · Income Tax Department. Last checked 24 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.