₹40 Lakh Home Loan EMI: ₹33,458 a Month (and How to Save ₹14 Lakh)
The EMI for a ₹40 lakh home loan is about ₹33,458 a month for 20 years at 8%. See EMI tables for every tenure, total interest, the salary you need and ways to save lakhs.
On this page 10 sections
- 01₹40 lakh home loan EMI table (by rate and tenure)
- 02Total interest on a ₹40 lakh home loan
- 03Interest vs principal: where your EMI goes
- 04What the October 2026 rate hike means for your EMI
- 05Salary needed for a ₹40 lakh home loan
- 06Down payment and extra costs
- 07Tax benefits on a ₹40 lakh home loan
- 08How to save ₹14 lakh+ on a ₹40 lakh loan
- 09Frequently asked questions
- 10Related guides and calculators
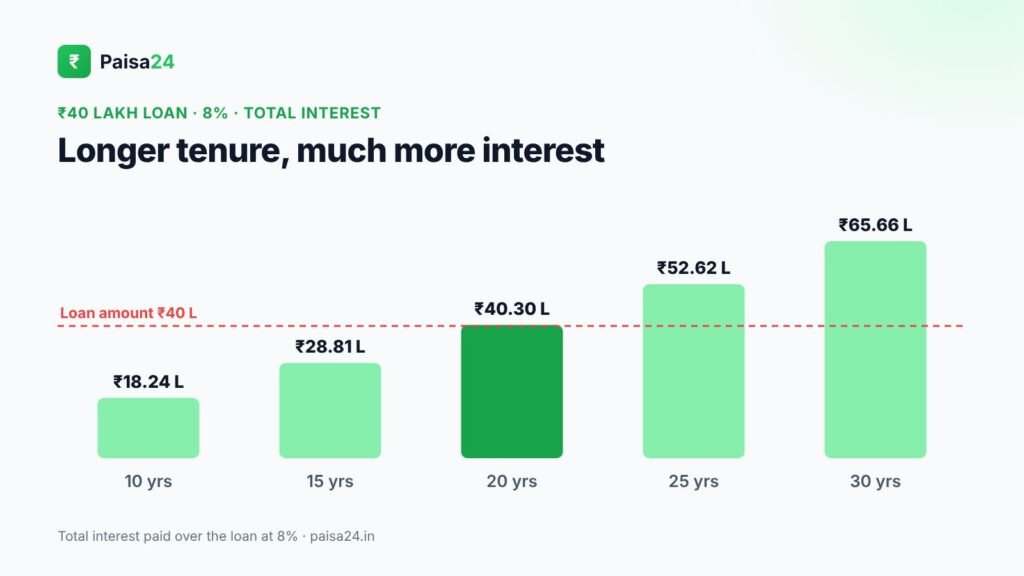
The EMI for a ₹40 lakh home loan is about ₹33,458 a month for 20 years at 8% interest. Choose 30 years and the EMI drops to ₹29,351, but total interest balloons to about ₹65.7 lakh, far more than the loan itself. Below are EMI tables for every common rate and tenure, what the October 2026 repo rate hike means for your EMI, the salary banks want, the down payment and two easy ways to save over ₹14 lakh.
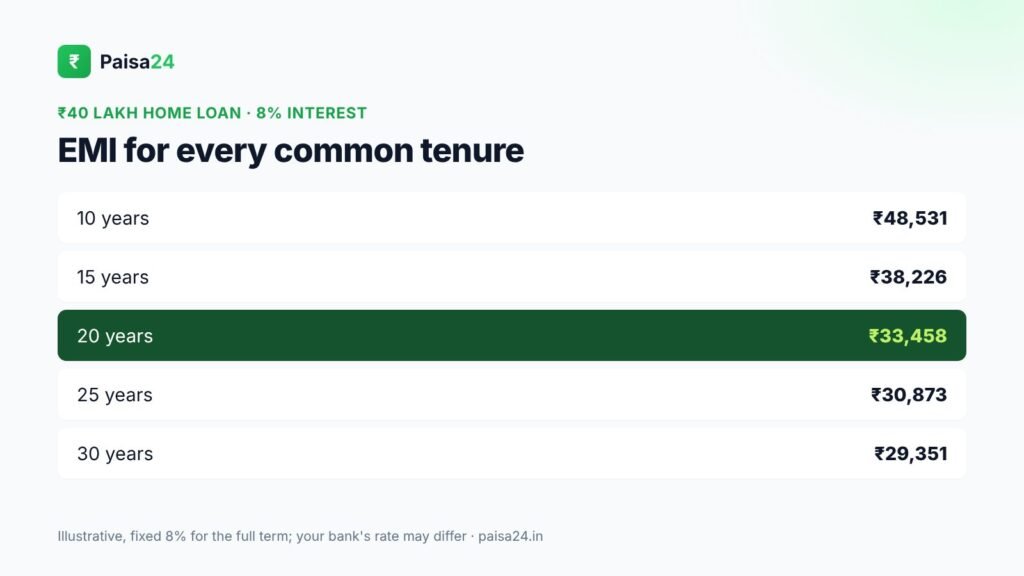
Quick answer: ₹40 lakh home loan EMI at 8%: ₹48,531 (10 years), ₹38,226 (15 years), ₹33,458 (20 years), ₹30,873 (25 years) and ₹29,351 (30 years).
Key takeaways
- ₹40 lakh for 20 years at 8%: EMI about ₹33,458, total interest about ₹40.3 lakh, so you repay roughly ₹80.3 lakh in all.
- Every ₹1 lakh of loan costs about ₹836 a month for 20 years at 8%.
- Banks usually want a take-home pay of about ₹67,000 a month for a 20-year ₹40 lakh loan, if you have no other EMIs.
- Raising your EMI by 5% a year saves about ₹14.2 lakh and closes the loan in about 12 years instead of 20.
- The RBI raised the repo rate to 5.50% in October 2026; a 0.25% rise adds about ₹635 a month to a 20-year ₹40 lakh EMI.
₹40 lakh home loan EMI table (by rate and tenure)
Most banks and housing finance companies price home loans between about 7.5% and 9.5% in late 2026, depending on your credit score, income type and the lender. Find your row below:
| Rate | 10 years | 15 years | 20 years | 25 years | 30 years |
|---|---|---|---|---|---|
| 7.5% | ₹47,481 | ₹37,080 | ₹32,224 | ₹29,560 | ₹27,969 |
| 8% | ₹48,531 | ₹38,226 | ₹33,458 | ₹30,873 | ₹29,351 |
| 8.5% | ₹49,594 | ₹39,390 | ₹34,713 | ₹32,209 | ₹30,757 |
| 9% | ₹50,670 | ₹40,571 | ₹35,989 | ₹33,568 | ₹32,185 |
| 9.5% | ₹51,759 | ₹41,769 | ₹37,285 | ₹34,948 | ₹33,634 |
EMI uses the standard formula EMI = P × r × (1 + r)n ÷ [(1 + r)n − 1], where P is the loan (₹40,00,000), r is the monthly rate (8% ÷ 12 = 0.667%) and n is the number of months (240 for 20 years).
Free calculatorCalculate the EMI for your loan amountHome, car & personal loan EMI with a full schedule.Total interest on a ₹40 lakh home loan
| Tenure | EMI at 8% | Total interest | Total repaid |
|---|---|---|---|
| 10 years | ₹48,531 | ₹18.24 lakh | ₹58.24 lakh |
| 15 years | ₹38,226 | ₹28.81 lakh | ₹68.81 lakh |
| 20 years | ₹33,458 | ₹40.30 lakh | ₹80.30 lakh |
| 25 years | ₹30,873 | ₹52.62 lakh | ₹92.62 lakh |
| 30 years | ₹29,351 | ₹65.66 lakh | ₹1.06 crore |
Going from 20 to 30 years cuts your EMI by only about ₹4,100 a month, but adds over ₹25 lakh of interest. A longer tenure is useful only to get approved or keep the EMI comfortable; plan to prepay so you do not actually stay for 30 years.
Interest vs principal: where your EMI goes
In the early years most of your EMI pays interest. For a 20-year ₹40 lakh loan at 8%:
| Loan year | Interest paid | Principal repaid | Balance at year end |
|---|---|---|---|
| Year 1 | ₹3,16,945 | ₹84,547 | ₹39,15,453 |
| Year 5 | ₹2,85,183 | ₹1,16,308 | ₹35,01,023 |
| Year 10 | ₹2,28,210 | ₹1,73,281 | ₹27,57,625 |
| Year 15 | ₹1,43,329 | ₹2,58,162 | ₹16,50,077 |
| Year 20 | ₹16,870 | ₹3,84,621 | ₹0 |
After 10 years you have paid about ₹40 lakh in EMIs but still owe about ₹27.6 lakh. That is why prepayments in the first five to seven years save the most.
What the October 2026 rate hike means for your EMI
On 7 October 2026 the RBI’s Monetary Policy Committee raised the repo rate by 0.25% to 5.50% and moved its stance to “calibrated tightening”. Most floating home loans are linked to the repo rate through an external benchmark (EBLR), so banks pass the change on within weeks, usually at the next reset date.
- A 0.25% rise (say 8.50% to 8.75%) adds about ₹635 a month to a 20-year ₹40 lakh EMI.
- Many banks extend your tenure instead of raising the EMI. Ask your lender to raise the EMI instead, because a longer tenure costs far more interest.
- If your current rate is more than 0.5% above what new borrowers get, consider a balance transfer, but check the processing fee first.
Salary needed for a ₹40 lakh home loan
Banks look at your FOIR (fixed obligations to income ratio). Most allow total EMIs of 40% to 50% of take-home pay. At a 50% FOIR and no other loans:
| Tenure (8%) | EMI | Minimum take-home pay |
|---|---|---|
| 15 years | ₹38,226 | about ₹76,500 a month |
| 20 years | ₹33,458 | about ₹67,000 a month |
| 30 years | ₹29,351 | about ₹58,700 a month |
A 12 LPA earner takes home about ₹85,000 a month (see 12 LPA in-hand salary), which comfortably covers a 20-year ₹40 lakh loan. Adding a co-applicant, such as an earning spouse, raises eligibility. A CIBIL score above 750 also gets you the lowest rates; here is how to improve your CIBIL score.
Free calculatorCheck how much home loan you can getHow big a home loan your salary can get you.Down payment and extra costs
RBI rules cap the loan-to-value (LTV) ratio at 80% for loans between ₹30 lakh and ₹75 lakh. So for a ₹40 lakh loan the property must be worth at least ₹50 lakh, and you pay the rest:
- Down payment: at least ₹10 lakh (20% of ₹50 lakh).
- Stamp duty and registration: about 5% to 8% of the property value, depending on the state (around ₹2.5 lakh to ₹4 lakh). Banks do not fund this.
- Processing fee: usually 0.25% to 1% of the loan, plus GST.
- Other costs: legal and valuation charges, home insurance, and interiors.
Tax benefits on a ₹40 lakh home loan
Tax benefits apply only if you choose the old tax regime and the house is self-occupied:
- Interest: up to ₹2 lakh a year deduction. In year 1 you pay about ₹3.17 lakh of interest, so you can claim the full ₹2 lakh.
- Principal: up to ₹1.5 lakh a year under the 80C limit, along with PF, PPF and ELSS. See the 80C deductions list.
- Joint loan: if both co-owners are co-borrowers, each can claim these limits separately.
In the new regime there is no deduction for a self-occupied home loan. Use our new vs old regime guide to see which saves more once you add these deductions.
How to save ₹14 lakh+ on a ₹40 lakh loan
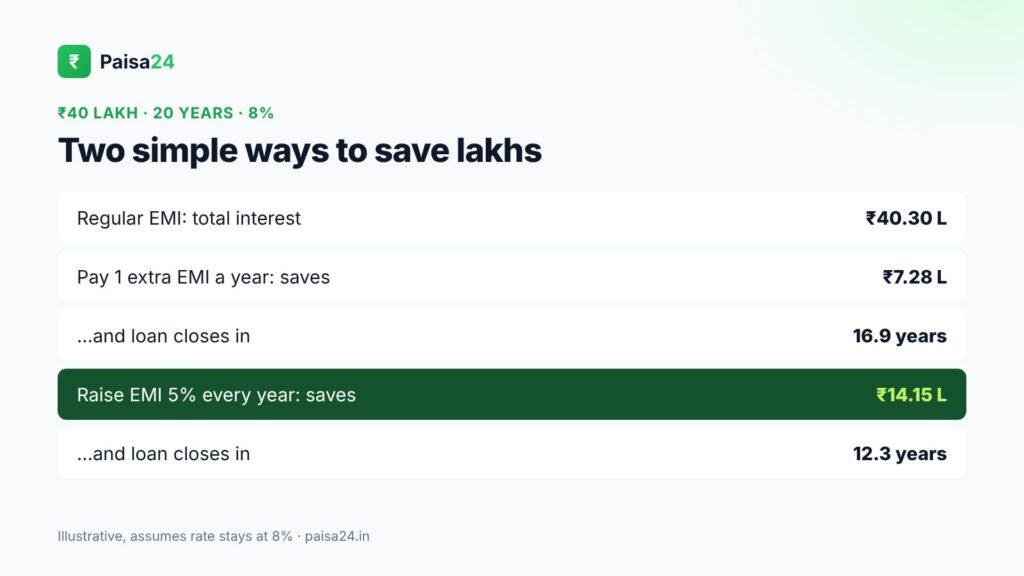
- Raise your EMI by 5% every year. Your salary rises anyway. This alone saves about ₹14.15 lakh of interest and closes a 20-year loan in about 12 years and 4 months.
- Pay one extra EMI a year. Using your bonus to pay one extra ₹33,458 each year saves about ₹7.28 lakh and finishes the loan around 3 years early.
- Prepay without penalty. RBI does not allow prepayment charges on floating-rate home loans taken by individuals, so prepay whenever you have spare cash. Read reduce EMI or tenure?
- Negotiate or switch. A 0.5% lower rate on ₹40 lakh over 20 years saves about ₹3 lakh.
Frequently asked questions
What is the EMI for a ₹40 lakh home loan for 20 years?
About ₹33,458 a month at 8%, ₹32,224 at 7.5% and ₹35,989 at 9%.
What is the EMI for ₹40 lakh for 30 years?
About ₹29,351 a month at 8%. Total interest over 30 years is about ₹65.7 lakh.
What salary is required for a ₹40 lakh home loan?
About ₹67,000 a month take-home for a 20-year loan at 8%, assuming no other EMIs and a 50% FOIR. With a 30-year tenure, about ₹59,000.
How much down payment do I need for a ₹40 lakh home loan?
At least ₹10 lakh, because banks fund only 80% of the property value for loans above ₹30 lakh, plus stamp duty and registration.
How much interest will I pay on a ₹40 lakh home loan?
About ₹40.3 lakh over 20 years at 8%, ₹28.8 lakh over 15 years and ₹65.7 lakh over 30 years.
Will my EMI go up after the October 2026 repo rate hike?
If your loan is floating and linked to the repo rate, yes, at your next reset. A 0.25% rise adds about ₹635 a month on a 20-year ₹40 lakh loan, or your bank may extend the tenure instead.
Related guides and calculators
- EMI for ₹30 lakh home loan
- EMI for ₹50 lakh home loan
- Home loan prepayment: reduce EMI or tenure?
- 12 LPA in-hand salary
- EMI calculator
- Home loan eligibility calculator
Sources: RBI · National Housing Bank · Income Tax Department. Last checked 30 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.