SIP of 2000 for 10, 15, 20 & 25 Years: How Much Will You Get?
A SIP of ₹2,000 a month can grow to about ₹19.98 lakh in 20 years at 12%. See the full returns table, the effect of a yearly step-up and how to start.
On this page 11 sections
- 01SIP of ₹2,000: returns table
- 02SIP of ₹2,000 for 10 years
- 03SIP of ₹2,000 for 15 years
- 04SIP of ₹2,000 for 20 years
- 05SIP of ₹2,000 for 25 and 30 years
- 06₹2,000 SIP with a 10% yearly step-up
- 07Why starting early matters
- 08₹2,000 vs other SIP amounts (20 years)
- 09How to start a ₹2,000 SIP
- 10Frequently asked questions
- 11Related guides and calculators
A SIP of ₹2,000 a month can grow to about ₹19.98 lakh in 20 years at a 12% annual return. In 10 years it becomes about ₹4.65 lakh, in 15 years about ₹10.09 lakh and in 25 years about ₹37.95 lakh. Below is the full returns table at 10%, 12% and 14%, the effect of a yearly step-up, the cost of starting late and how to start a ₹2,000 SIP today.
Quick answer: ₹2,000 SIP at 12%: ₹4.65 lakh in 10 years, ₹10.09 lakh in 15 years, ₹19.98 lakh in 20 years and ₹37.95 lakh in 25 years.
Key takeaways
- SIP of ₹2,000 for 20 years: you invest ₹4.8 lakh and it grows to about ₹19.98 lakh at 12%.
- Over 25 years the gain (₹31.95 lakh) is more than five times what you put in.
- Raising the SIP by 10% every year roughly doubles the 20-year result to about ₹39.78 lakh.
- Starting at 25 instead of 35 turns the same ₹2,000 into about ₹1.3 crore by 60 instead of ₹38 lakh.
- Long-term equity gains above ₹1.25 lakh a year are taxed at 12.5%.
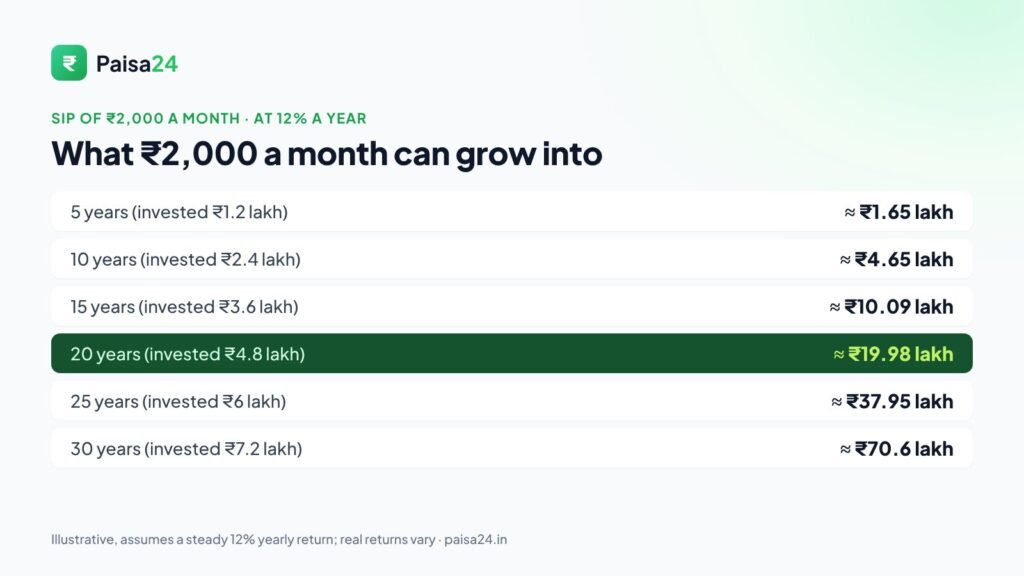
SIP of ₹2,000: returns table
| Period | Invested | At 10% | At 12% | At 14% |
|---|---|---|---|---|
| 5 years | ₹1.2 lakh | ₹1.56 lakh | ₹1.65 lakh | ₹1.74 lakh |
| 10 years | ₹2.4 lakh | ₹4.13 lakh | ₹4.65 lakh | ₹5.24 lakh |
| 15 years | ₹3.6 lakh | ₹8.36 lakh | ₹10.09 lakh | ₹12.26 lakh |
| 20 years | ₹4.8 lakh | ₹15.31 lakh | ₹19.98 lakh | ₹26.33 lakh |
| 25 years | ₹6 lakh | ₹26.76 lakh | ₹37.95 lakh | ₹54.55 lakh |
| 30 years | ₹7.2 lakh | ₹45.59 lakh | ₹70.60 lakh | ₹1.11 crore |
SIP of ₹2,000 for 10 years
Over 10 years you invest ₹2.4 lakh. At 12% it grows to about ₹4.65 lakh, a gain of ₹2.25 lakh. At 10% it is about ₹4.13 lakh. Ten years is the minimum period we suggest for an equity SIP, because shorter periods can end in a market fall.
SIP of ₹2,000 for 15 years
Over 15 years you invest ₹3.6 lakh and it grows to about ₹10.09 lakh at 12%. This is where compounding starts to show: the gain (₹6.49 lakh) is now nearly double your investment.
SIP of ₹2,000 for 20 years
Over 20 years you invest ₹4.8 lakh and it grows to about ₹19.98 lakh at 12%, more than four times your money. Notice that the last five years add almost as much as the first fifteen: compounding works hardest at the end, so the biggest mistake is stopping early.
SIP of ₹2,000 for 25 and 30 years
Over 25 years your ₹6 lakh grows to about ₹37.95 lakh, and over 30 years ₹7.2 lakh becomes about ₹70.6 lakh at 12%. A small, steady SIP started in your 20s can fund a large part of your retirement on its own.
₹2,000 SIP with a 10% yearly step-up
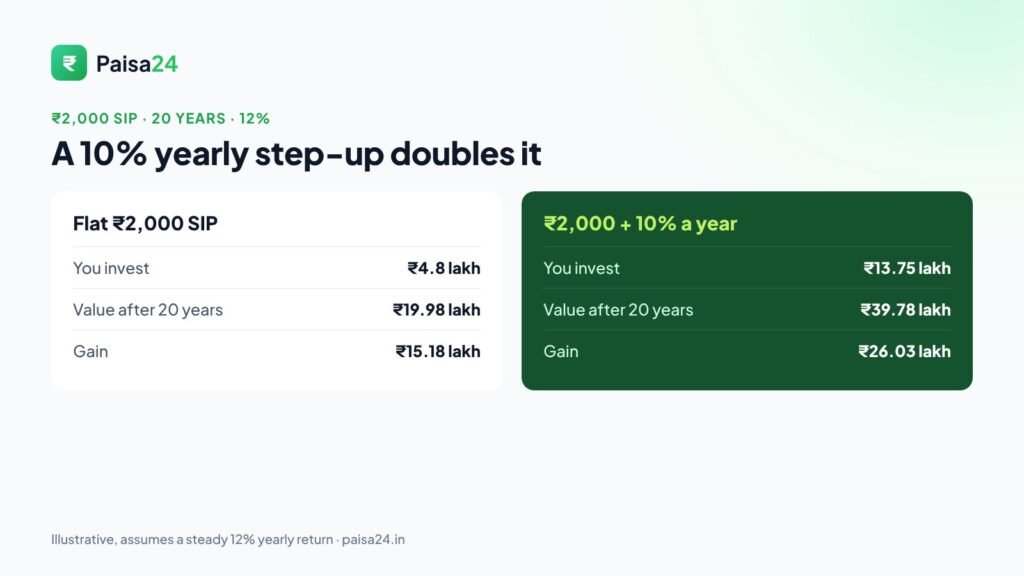
Most people earn more each year, so raising your SIP with your increment is the easiest way to grow wealth. If you start at ₹2,000 and add 10% every year:
| Period | Total invested | Value at 12% | Flat ₹2,000 SIP value |
|---|---|---|---|
| 10 years | ₹3.82 lakh | ₹6.75 lakh | ₹4.65 lakh |
| 15 years | ₹7.63 lakh | ₹17.37 lakh | ₹10.09 lakh |
| 20 years | ₹13.75 lakh | ₹39.78 lakh | ₹19.98 lakh |
| 25 years | ₹23.6 lakh | ₹85.51 lakh | ₹37.95 lakh |
Tip: Most fund houses and apps let you set an automatic yearly top-up when you start the SIP. Turn it on once and you never have to remember.
Why starting early matters
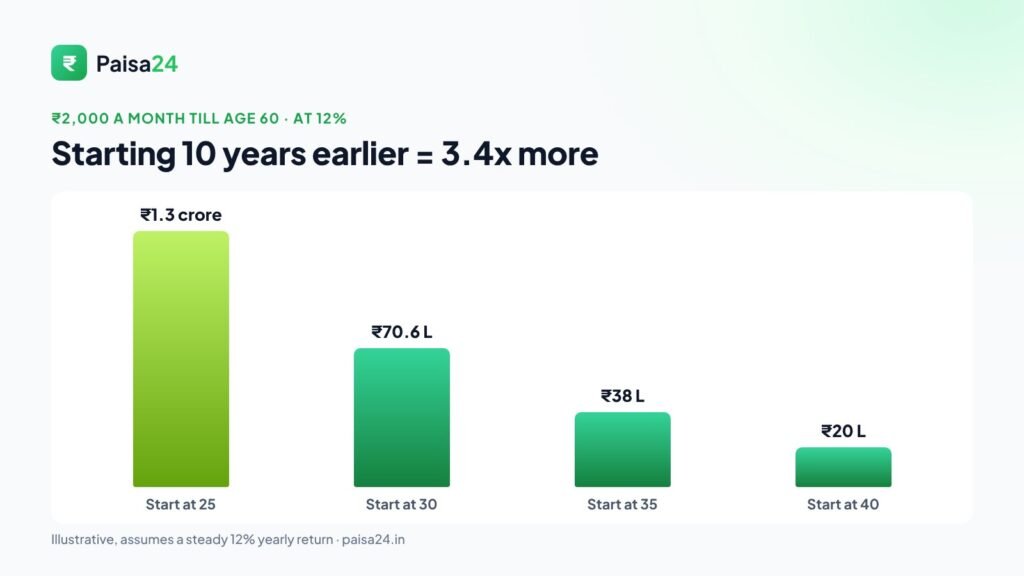
| Start age | Years till 60 | Total invested | Value at 60 (12%) |
|---|---|---|---|
| 25 | 35 | ₹8.4 lakh | about ₹1.3 crore |
| 30 | 30 | ₹7.2 lakh | about ₹70.6 lakh |
| 35 | 25 | ₹6 lakh | about ₹37.95 lakh |
| 40 | 20 | ₹4.8 lakh | about ₹19.98 lakh |
Starting 10 years earlier costs only ₹2.4 lakh more in total investment, but the end value is about 3.4 times higher. Time in the market matters more than the amount.
₹2,000 vs other SIP amounts (20 years)
| Monthly SIP | Invested in 20 years | Value at 12% |
|---|---|---|
| ₹1,000 | ₹2.4 lakh | ₹9.99 lakh |
| ₹2,000 | ₹4.8 lakh | ₹19.98 lakh |
| ₹3,000 | ₹7.2 lakh | ₹29.97 lakh |
| ₹5,000 | ₹12 lakh | ₹49.96 lakh |
| ₹10,000 | ₹24 lakh | ₹99.91 lakh |
How to start a ₹2,000 SIP
- Complete your KYC with PAN and Aadhaar on any fund house website or investment app.
- Pick one diversified fund, such as a Nifty 50 index fund or a flexi-cap fund, in the direct plan, which costs less than a regular plan.
- Choose a SIP date a few days after your salary arrives, and set up an auto-debit mandate.
- Add a yearly step-up of 10% if the app allows it.
- Review once a year, not every day. Do not stop the SIP when markets fall; that is when your SIP buys more units.
Tax on SIP returns
| Holding period (equity funds) | Tax rate |
|---|---|
| More than 12 months (long-term) | 12.5% on gains above ₹1.25 lakh a year |
| Up to 12 months (short-term) | 20% |
With a ₹2,000 SIP your yearly gains will often stay under the ₹1.25 lakh tax-free limit if you redeem in parts across years. If you also want a tax deduction under the old regime, an ELSS fund qualifies under Section 80C, with a 3-year lock-in for each instalment.
Watch out: 12% is an assumption, not a promise. Equity funds can fall 20% to 30% in a bad year. Keep an emergency fund separately so you never have to stop or redeem your SIP in a crash.
Frequently asked questions
How much will ₹2,000 SIP become in 20 years?
About ₹19.98 lakh at 12%, ₹15.31 lakh at 10% and ₹26.33 lakh at 14%, on a total investment of ₹4.8 lakh.
How much will ₹2,000 SIP give in 10 years?
About ₹4.65 lakh at 12% on a total investment of ₹2.4 lakh.
How much will ₹2,000 SIP give in 15 years?
About ₹10.09 lakh at 12% on a total investment of ₹3.6 lakh.
Can ₹2,000 SIP make ₹1 crore?
Yes, but it takes time: about 33 years at 12%. With a 10% yearly step-up you can reach ₹1 crore in about 26 years.
Is ₹2,000 a month enough to start a SIP?
Yes. Many funds accept SIPs from ₹100 to ₹500. ₹2,000 is a solid start, and raising it each year matters more than the starting amount.
Which fund is best for a ₹2,000 SIP?
For most beginners a low-cost Nifty 50 index fund or a flexi-cap fund in the direct plan is a simple choice. Pick based on your goal and time horizon, not past one-year returns.
Related guides and calculators
- SIP of ₹5,000 for 10, 15 & 20 years
- SIP of ₹10,000 for 10 to 25 years
- How much SIP for ₹1 crore?
- SIP calculator
Sources: AMFI · SEBI · Income Tax Department. Last checked 28 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.