PPF ₹1.5 Lakh a Year for 15 Years: Maturity Amount (2026)
Investing ₹1.5 lakh a year in PPF for 15 years gives about ₹40.68 lakh at 7.1%. See maturity for every deposit, extension to 30 years and key PPF rules.
On this page 8 sections
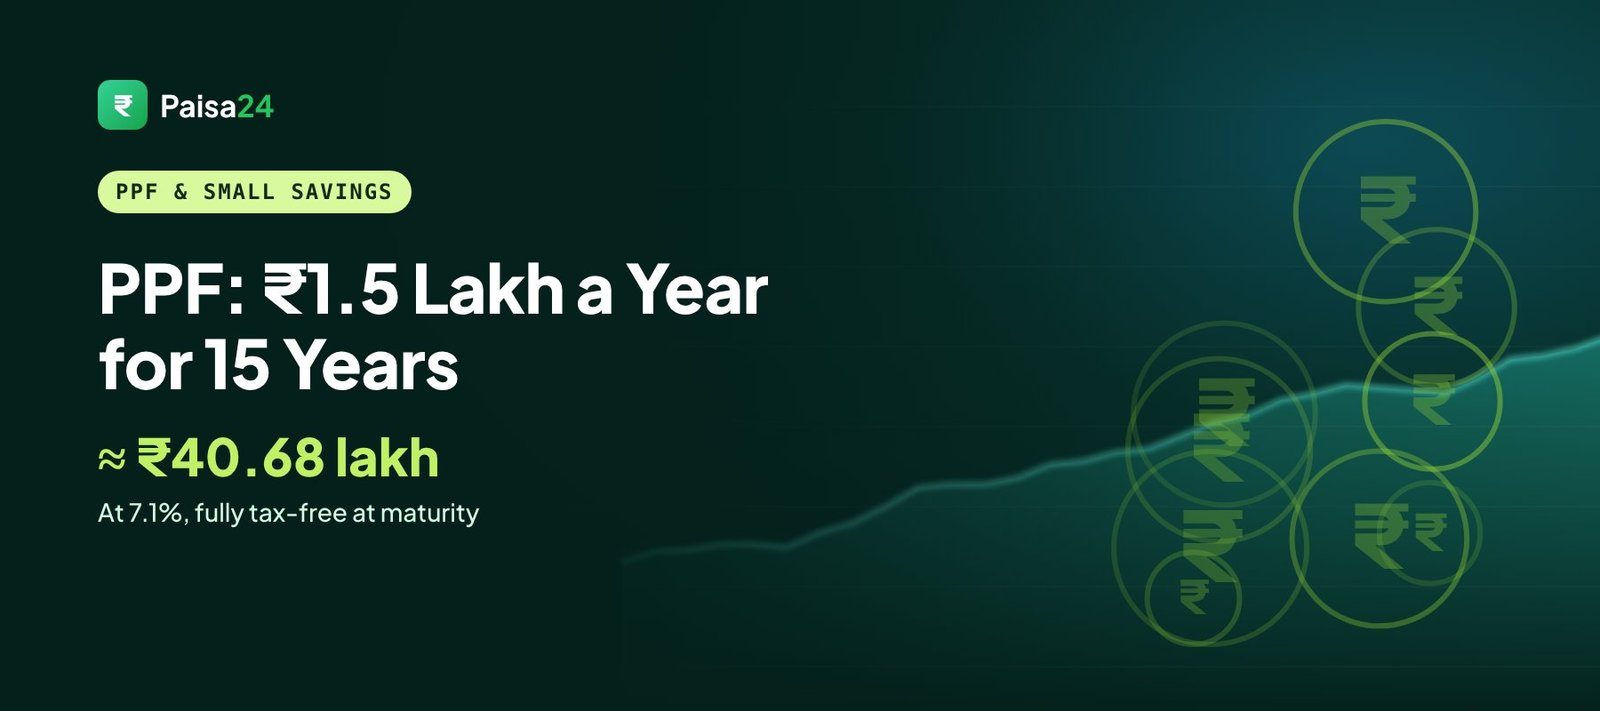
If you invest ₹1.5 lakh a year in PPF for 15 years, you get about ₹40.68 lakh at maturity at the current 7.1% interest rate. You put in ₹22.5 lakh, so about ₹18.18 lakh is interest, and the whole amount is tax-free. Below is the maturity for every yearly deposit, what happens if you extend to 20, 25 or 30 years, the deposit-date trick that adds over ₹1 lakh, and all the key PPF rules.
Quick answer: PPF ₹1.5 lakh a year at 7.1%: ₹40.68 lakh after 15 years, ₹66.58 lakh after 20 years, ₹1.03 crore after 25 years and ₹1.55 crore after 30 years.
Key takeaways
- ₹1.5 lakh a year in PPF for 15 years grows to about ₹40.68 lakh at 7.1%.
- The PPF rate is 7.1% for October to December 2026, unchanged since April 2020.
- Deposit before 5 April each year to earn interest for the full year.
- Extending in 5-year blocks turns the same ₹1.5 lakh a year into about ₹1.03 crore after 25 years.
- Interest and maturity are tax-free; the deduction on deposits is available only in the old regime.
PPF maturity for ₹1.5 lakh a year (15 years)
PPF interest is calculated monthly on the lowest balance between the 5th and the last day of the month, and credited once a year on 31 March. If you deposit the full ₹1.5 lakh before 5 April, your balance grows like this:
| End of year | Total deposited | Balance at 7.1% |
|---|---|---|
| 1 | ₹1.5 lakh | ₹1,60,650 |
| 3 | ₹4.5 lakh | ₹5,16,978 |
| 5 | ₹7.5 lakh | ₹9,25,701 |
| 7 | ₹10.5 lakh | ₹13,94,524 |
| 10 | ₹15 lakh | ₹22,30,124 |
| 12 | ₹18 lakh | ₹28,90,750 |
| 15 | ₹22.5 lakh | ₹40,68,209 |
PPF maturity for other yearly deposits
| Yearly deposit | Total deposited (15 years) | Maturity at 7.1% | Interest earned |
|---|---|---|---|
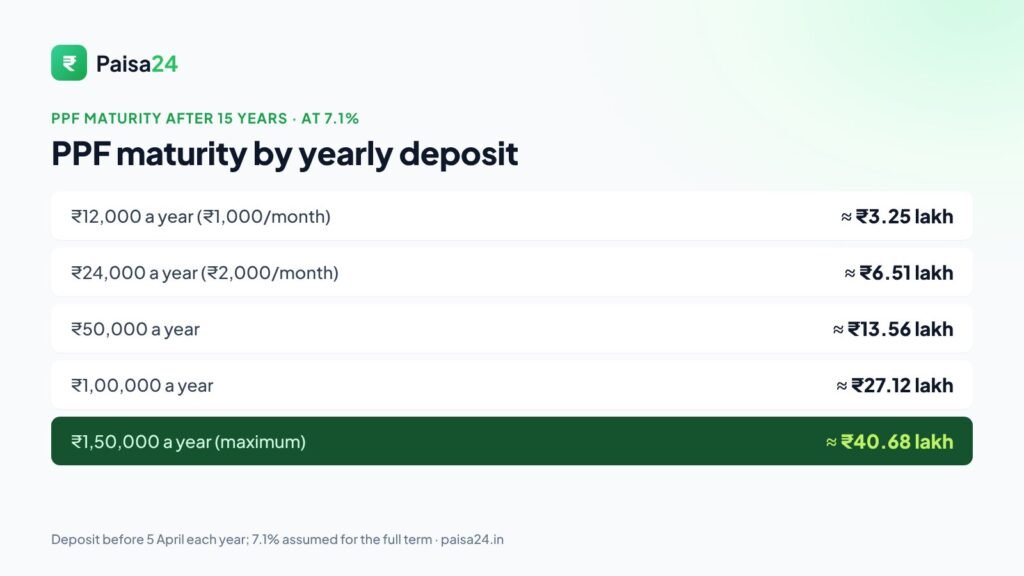
| ₹12,000 (₹1,000/month) | ₹1.8 lakh | ₹3,25,457 | ₹1,45,457 |
| ₹24,000 (₹2,000/month) | ₹3.6 lakh | ₹6,50,913 | ₹2,90,913 |
| ₹50,000 | ₹7.5 lakh | ₹13,56,070 | ₹6,06,070 |
| ₹1,00,000 | ₹15 lakh | ₹27,12,139 | ₹12,12,139 |
| ₹1,50,000 | ₹22.5 lakh | ₹40,68,209 | ₹18,18,209 |
Lump sum by 5 April vs ₹12,500 a month
Many people deposit ₹12,500 a month instead of ₹1.5 lakh at once. Even if you deposit before the 5th of every month, you earn slightly less, because money deposited later in the year earns interest for fewer months:
| Deposit pattern | 15 years | 20 years | 25 years |
|---|---|---|---|
| ₹1.5 lakh before 5 April | ₹40.68 lakh | ₹66.58 lakh | ₹1.03 crore |
| ₹12,500 before 5th of each month | ₹39.45 lakh | ₹64.56 lakh | ₹99.95 lakh |
The difference is about ₹1.23 lakh over 15 years. If you get an annual bonus or have savings in a bank account, move it to PPF in the first days of April.
Extending PPF after 15 years
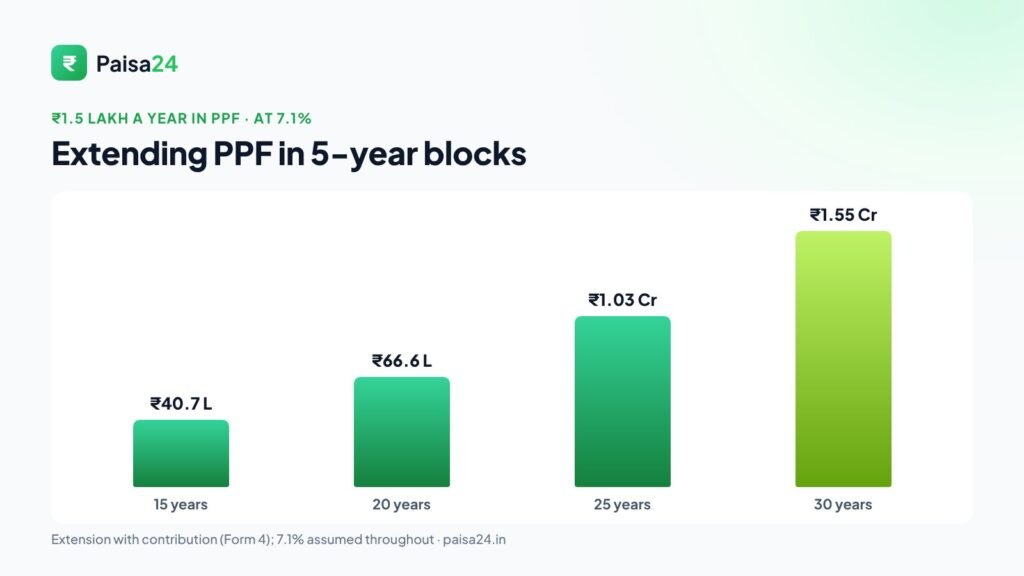
After 15 years you can extend your PPF account in blocks of 5 years, as many times as you like. You can extend with contributions (submit Form 4 within one year of maturity) or without contributions (the balance keeps earning interest automatically).
| Total period | Total deposited | Balance at 7.1% |
|---|---|---|
| 15 years | ₹22.5 lakh | ₹40.68 lakh |
| 20 years | ₹30 lakh | ₹66.58 lakh |
| 25 years | ₹37.5 lakh | ₹1.03 crore |
| 30 years | ₹45 lakh | ₹1.55 crore |
If you open a PPF account at 25 and keep extending till 55, the same ₹1.5 lakh a year can build a tax-free corpus of about ₹1.55 crore. During an extension with contributions, you can withdraw up to 60% of the balance at the start of that block, once a year.
PPF rules you should know
| Rule | Details |
|---|---|
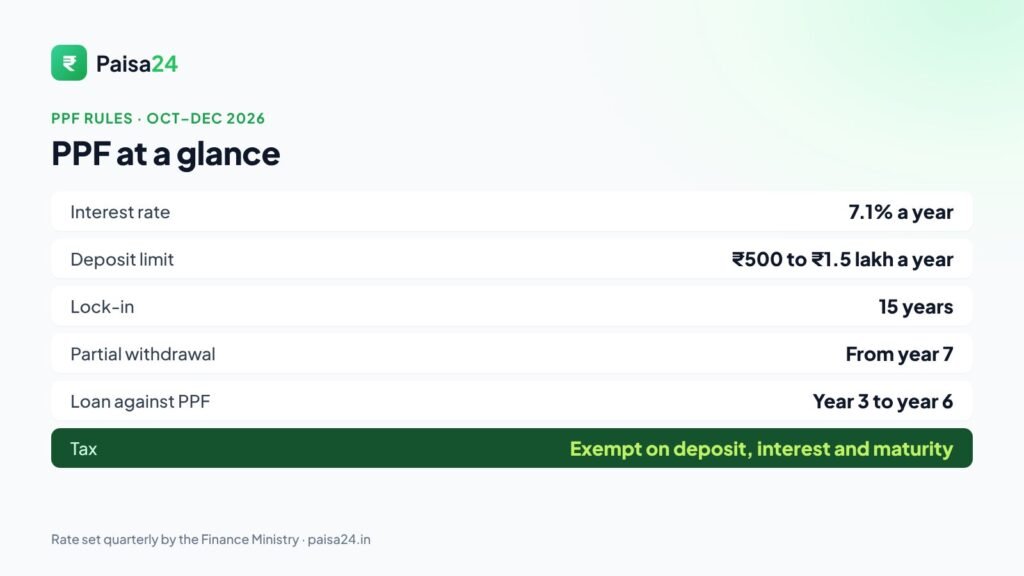
| Interest rate | 7.1% a year (Oct–Dec 2026), set every quarter by the Finance Ministry |
| Deposit | Minimum ₹500 and maximum ₹1.5 lakh per financial year, in multiples of ₹50 |
| Lock-in | 15 full financial years from the end of the year you open it |
| Partial withdrawal | Once a year from year 7, up to 50% of the balance at the end of the 4th preceding year or the previous year, whichever is lower |
| Loan | From year 3 to year 6, up to 25% of the balance at the end of the 2nd preceding year, at 1% above the PPF rate |
| Premature closure | After 5 years, only for serious illness, higher education or change of residency, with a 1% interest cut |
| Missed deposit | Account becomes inactive; revive with ₹500 plus ₹50 penalty for each missed year |
Is PPF tax-free?
PPF is an EEE (exempt-exempt-exempt) investment: the interest you earn and the maturity amount are fully tax-free in both tax regimes. The deduction of up to ₹1.5 lakh on your deposits, however, is available only in the old regime under Section 80C. In the new regime you still get tax-free interest, which is valuable on its own.
To match PPF’s 7.1% tax-free return, a fully taxable FD would need to pay about 10.3% if you are in the 30% slab (with cess), or about 9% in the 20% slab.
Tip: Open a PPF account even if you deposit only ₹500 a year for now. The 15-year clock starts from the year you open it, so an early start gives you an earlier maturity and more freedom to extend later.
PPF vs SIP: which is better?
PPF gives a guaranteed, tax-free return and suits the safe part of your long-term savings. An equity SIP can earn more over 15 to 20 years but can fall in the short term. Many people use both: PPF for stability and an equity SIP for growth. Compare the numbers in our SIP of ₹10,000 guide.
Frequently asked questions
How much will I get if I invest ₹1.5 lakh in PPF for 15 years?
About ₹40.68 lakh at the current 7.1% rate, if you deposit ₹1.5 lakh before 5 April every year. Total deposits are ₹22.5 lakh.
What is the current PPF interest rate?
7.1% a year for October to December 2026. The government reviews it every quarter.
Can I invest more than ₹1.5 lakh in PPF?
No. ₹1.5 lakh is the maximum per financial year across your own account and accounts you open for minors. Extra deposits earn no interest.
Is PPF maturity taxable?
No. Both the interest and the maturity amount are tax-free in the old and new regimes.
What happens to PPF after 15 years?
You can close it and take the money, or extend it in 5-year blocks with or without fresh deposits.
When should I deposit in PPF for maximum interest?
Before 5 April each year. Monthly deposits should be made before the 5th of the month.
Related guides and calculators
- Small savings interest rates Oct–Dec 2026
- 80C deductions list 2026-27
- SIP of ₹2,000 for 10 to 25 years
- PPF calculator
Sources: National Savings Institute · India Post · Ministry of Finance · Income Tax Department. Last checked 28 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.