12 LPA In-Hand Salary: ₹85,387 a Month and ₹0 Tax (FY 2026-27)
12 LPA in-hand salary is about ₹85,387 a month in FY 2026-27, and you pay zero income tax in the new regime. See the full breakup of PF, gratuity and tax.
On this page 10 sections
- 0112 LPA in-hand salary: full calculation
- 02How much tax on 12 LPA? Why it is zero
- 03Monthly payslip for 12 LPA
- 04In-hand salary if PF is capped at ₹1,800
- 05In-hand salary for 11 to 14 LPA
- 06New vs old regime at 12 LPA
- 07How to increase your take-home on 12 LPA
- 08What can you afford on ₹85,000 a month?
- 09Frequently asked questions
- 10Related guides and calculators
On a 12 LPA salary, your in-hand pay is about ₹85,387 a month (₹10,24,640 a year) in FY 2026-27, and you pay zero income tax in the new regime. That assumes basic pay is 50% of CTC and PF is cut on full basic. If your employer caps PF at ₹1,800 a month, take-home rises to about ₹93,787 a month. Below is the full calculation, a sample payslip, a table for nearby CTCs and the one mistake that can quietly cost you tax at this salary.
Quick answer: 12 LPA in hand = about ₹85,000 to ₹94,000 a month, depending on how your PF is calculated. Income tax on 12 LPA is ₹0 in the new regime because your taxable income (about ₹10.24 lakh) is under the ₹12 lakh rebate limit.
Key takeaways
- 12 LPA in-hand salary: about ₹85,387 a month with PF on full basic, or ₹93,787 with PF capped at ₹1,800.
- Tax is zero in the new regime: after PF, gratuity and the ₹75,000 standard deduction, taxable income is about ₹10.24 lakh.
- A “12 lakh CTC” is not the same as “₹12 lakh taxable income”. With a typical salary structure you can earn up to about 13.9 LPA and still pay no tax.
- About ₹1.44 lakh a year goes into your EPF (your share plus your employer’s), earning 8.25% interest.
- The old regime only matches the new one at 12 LPA if you claim over ₹6 lakh of deductions, so most people should stay in the new regime.
12 LPA in-hand salary: full calculation
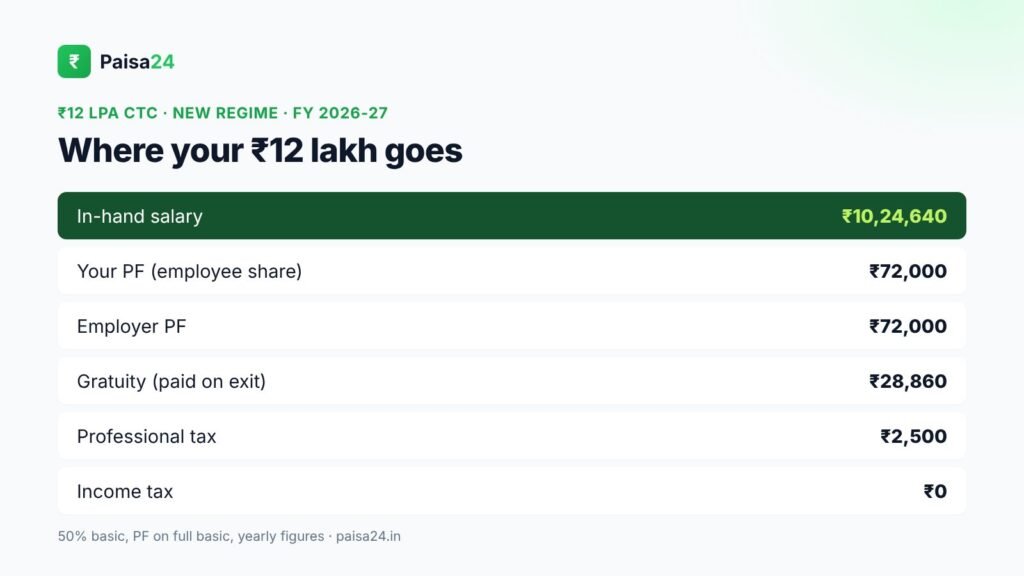
We assume a common private-sector structure: basic pay is 50% of CTC (the minimum “wages” share under the new labour codes), employer PF is 12% of basic and gratuity is 4.81% of basic. Both employer PF and gratuity are part of your CTC but never reach your bank account each month.
| Component | Yearly amount |
|---|---|
| CTC | ₹12,00,000 |
| Basic pay (50% of CTC) | ₹6,00,000 |
| Less: employer PF (12% of basic) | ₹72,000 |
| Less: gratuity (4.81% of basic) | ₹28,860 |
| = Gross salary | ₹10,99,140 |
| Less: employee PF (12% of basic) | ₹72,000 |
| Less: professional tax | ₹2,500 |
| Less: income tax (new regime) | ₹0 |
| = In-hand salary (yearly) | ₹10,24,640 |
| In-hand per month | ₹85,387 |
- Employer PF and your PF (₹72,000 each): ₹1.44 lakh a year builds up in your EPF account at 8.25% (the FY 2025-26 rate). It is your money, just locked for retirement.
- Gratuity (₹28,860): you get it only after five years of service with the same employer. See our gratuity calculation guide.
- Professional tax (₹2,500): charged by states like Karnataka, Maharashtra and West Bengal. It is nil in Delhi, Haryana and Uttar Pradesh, which adds about ₹208 a month to your take-home.
How much tax on 12 LPA? Why it is zero
Your gross salary of ₹10,99,140 becomes ₹10,24,140 after the ₹75,000 standard deduction. In the new regime for FY 2026-27, anyone with taxable income up to ₹12 lakh gets a full rebate, so the tax due is nil. Here is the slab working for reference:
| Slab (taxable income) | Rate | Tax |
|---|---|---|
| Up to ₹4,00,000 | Nil | ₹0 |
| ₹4,00,001 – ₹8,00,000 | 5% | ₹20,000 |
| ₹8,00,001 – ₹10,24,140 | 10% | ₹22,414 |
| Tax before rebate | ₹42,414 | |
| Less: rebate (taxable income under ₹12 lakh) | – ₹42,414 | |
| Tax payable | ₹0 |
The 12 lakh confusion: the ₹12 lakh limit applies to taxable income, not CTC. Because employer PF, gratuity and the standard deduction come off first, a salaried person with 50% basic pays no tax until a CTC of roughly ₹13.9 lakh. If your basic is lower or PF is capped, that ceiling is lower, so always run your own numbers.
Monthly payslip for 12 LPA
This is how a typical 12 LPA payslip looks in the new regime. Your company may split allowances differently, but the net pay will be close.
| Payslip line | Monthly amount |
|---|---|
| Basic pay | ₹50,000 |
| House rent allowance (HRA) | ₹25,000 |
| Special allowance | ₹16,595 |
| Gross monthly pay | ₹91,595 |
| Less: employee PF | ₹6,000 |
| Less: TDS (income tax) | ₹0 |
| Less: professional tax | ₹208 |
| Net pay | ₹85,387 |
In-hand salary if PF is capped at ₹1,800
Many companies calculate PF on a wage ceiling of ₹15,000 a month, so both your share and the employer share are ₹1,800 a month (₹21,600 a year). The rest of the CTC is paid out as salary instead.
| Component | PF on full basic | PF capped |
|---|---|---|
| Gross salary | ₹10,99,140 | ₹11,49,540 |
| Employee PF | ₹72,000 | ₹21,600 |
| Taxable income | ₹10,24,140 | ₹10,74,540 |
| Income tax | ₹0 | ₹0 |
| In-hand per month | ₹85,387 | ₹93,787 |
A capped PF gives you about ₹8,400 more each month, but you save about ₹1 lakh less a year for retirement. If you are disciplined, the extra cash can go into a monthly SIP instead.
In-hand salary for 11 to 14 LPA
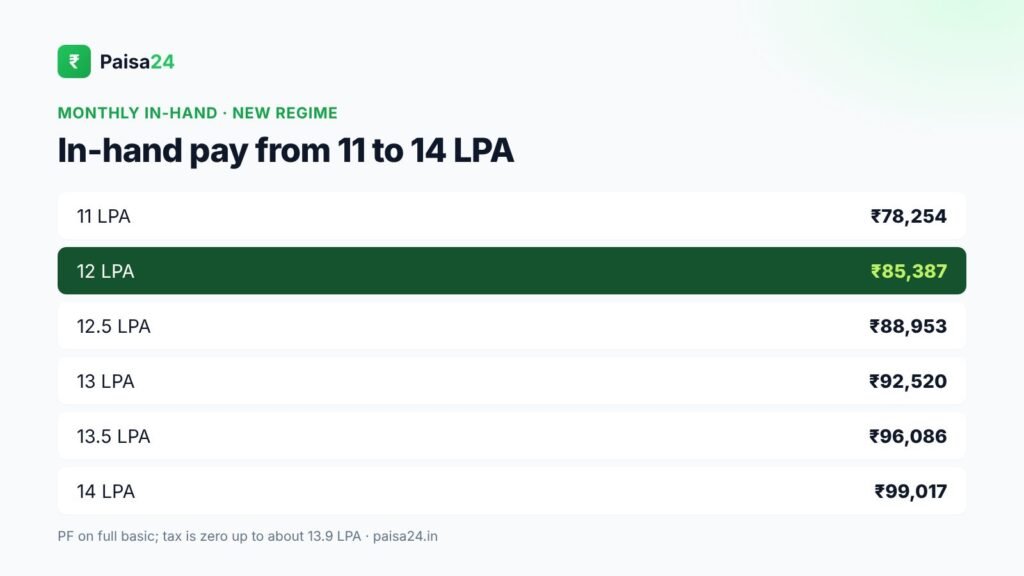
| CTC | Taxable income | Yearly tax | In-hand/month (full PF) | In-hand/month (capped PF) |
|---|---|---|---|---|
| 11 LPA | ₹9,32,545 | ₹0 | ₹78,254 | ₹85,654 |
| 12 LPA | ₹10,24,140 | ₹0 | ₹85,387 | ₹93,787 |
| 12.5 LPA | ₹10,69,938 | ₹0 | ₹88,953 | ₹97,853 |
| 13 LPA | ₹11,15,735 | ₹0 | ₹92,520 | ₹1,01,920 |
| 13.5 LPA | ₹11,61,532 | ₹0 | ₹96,086 | ₹1,04,172 |
| 14 LPA | ₹12,07,330 | ₹7,623 | ₹99,017 | ₹1,04,009 |
Notice the jump at 14 LPA: taxable income crosses ₹12 lakh, so a small tax starts. Thanks to marginal relief, you never pay more tax than the income above ₹12 lakh, so a raise never reduces your take-home. For higher packages see 15 LPA in-hand salary and 20 LPA in-hand salary.
New vs old regime at 12 LPA
In the old regime you get a ₹50,000 standard deduction plus deductions such as 80C, 80D, HRA and home loan interest, but the slabs are steeper. At 12 LPA, here is the old regime tax for different levels of deductions:
| Deductions claimed (old regime) | Total deductions | Old regime tax | New regime tax |
|---|---|---|---|
| Standard deduction + 80C + professional tax | ₹2,02,500 | ₹95,501 | ₹0 |
| + 80D health cover + ₹50,000 NPS | ₹2,77,500 | ₹79,901 | ₹0 |
| + HRA exemption of ₹1.5 lakh | ₹4,27,500 | ₹48,701 | ₹0 |
| + ₹2 lakh home loan interest | ₹6,27,500 | ₹0 | ₹0 |
The verdict is clear: the new regime wins at 12 LPA unless you have a large rent bill and a home loan at the same time. Even then it only ties. Our new vs old regime guide shows the break-even for every salary.
How to increase your take-home on 12 LPA
- Ask for employer NPS. Up to 14% of basic in employer NPS is deductible even in the new regime. It does not raise take-home today, but it keeps you in the zero-tax zone after your next raise.
- Check the PF basis. If cash flow is tight, ask HR whether PF can be calculated on the ₹15,000 wage ceiling. Weigh it against the retirement savings you give up.
- Claim reimbursements. Phone, internet and fuel reimbursements against bills are not taxed as salary, which matters once you cross the rebate limit.
- Submit investment proofs early. If you opted for the old regime, a late proof means extra TDS until you file your return.
- Negotiate the next raise smartly. Up to about 13.9 LPA is still tax-free with this structure, so every rupee of a raise up to that point reaches your pocket, minus PF.
What can you afford on ₹85,000 a month?
Using the popular 50-30-20 budget, a ₹85,387 take-home gives you about ₹42,700 for needs (rent, groceries, EMIs), ₹25,600 for wants and ₹17,000 for savings. Banks usually allow total EMIs of 40% to 50% of take-home pay, so you could afford a home loan EMI of around ₹34,000 to ₹42,000, which is roughly a ₹40 lakh home loan over 20 years.
Frequently asked questions
What is the in-hand salary for 12 LPA?
About ₹85,387 a month if PF is deducted on full basic, and about ₹93,787 a month if PF is capped at ₹1,800, in the new regime for FY 2026-27.
How much tax do I pay on a 12 lakh salary?
Zero in the new regime. After PF, gratuity and the ₹75,000 standard deduction, your taxable income is about ₹10.24 lakh, which is fully covered by the rebate for income up to ₹12 lakh.
Is 12 LPA a good salary in India?
Yes. A take-home of ₹85,000 to ₹94,000 a month is well above the national average and is comfortable in most cities if you keep rent under about ₹25,000.
What is the monthly gross salary for 12 LPA?
About ₹91,595 a month before PF and professional tax, assuming basic is 50% of CTC.
Up to what CTC is salary tax-free in FY 2026-27?
With 50% basic and PF on full basic, about ₹13.9 lakh CTC. The exact limit depends on your salary structure, because the ₹12 lakh rebate applies to taxable income, not CTC.
Should I choose the old regime at 12 LPA?
Almost never. You would need more than ₹6 lakh of deductions just to match the new regime’s zero tax.
Related guides and calculators
- 10 LPA in-hand salary
- 15 LPA in-hand salary
- CTC vs in-hand salary explained
- Income tax slabs FY 2026-27
- Salary calculator
- Income tax calculator
Sources: Income Tax Department · EPFO · Ministry of Labour and Employment. Last checked 30 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.