20 LPA In-Hand Salary: Monthly Take-Home After Tax (FY 2026-27)
20 LPA in-hand salary is about ₹1,29,330 a month in the new regime. See the full breakup of PF, gratuity, tax and take-home pay for FY 2026-27.
On this page 11 sections
- 0120 LPA in-hand salary: full calculation
- 02How much tax on 20 LPA? Slab-by-slab working
- 03Monthly payslip for 20 LPA
- 04How to cut tax on 20 LPA (legally)
- 05In-hand salary under different structures
- 06New vs old regime at 20 LPA
- 07In-hand salary for other CTCs (FY 2026-27)
- 08How to budget ₹1.29 lakh a month
- 09How to increase your take-home pay
- 10Frequently asked questions
- 11Related guides and calculators
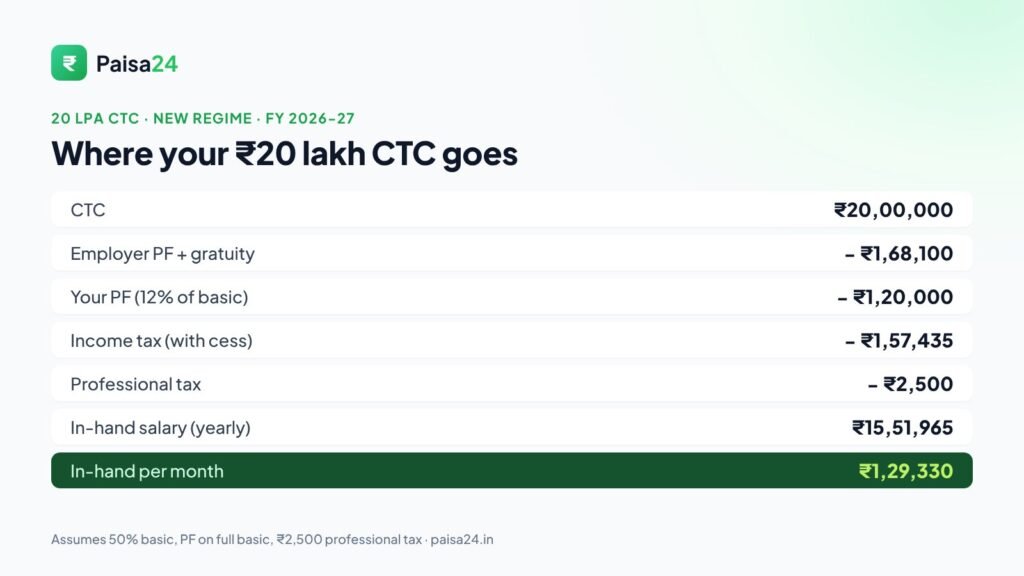
On a 20 LPA salary, your in-hand pay is about ₹1,29,330 a month (₹15,51,965 a year) in the new tax regime for FY 2026-27, assuming basic pay is 50% of CTC and PF is on full basic. Income tax is about ₹1,57,435 a year. If your employer caps PF at ₹1,800 a month, take-home rises to about ₹1,44,025. Below is the full breakup, the slab-by-slab tax, a sample payslip, and three legal ways to cut the tax.
Quick answer: 20 LPA in hand = about ₹1.29 lakh to ₹1.44 lakh a month, depending on how your PF is set up. Tax on 20 LPA is about ₹1,57,435 a year (₹13,120 a month) in the new regime, and employer NPS can cut it by ₹51,839.
Key takeaways
- 20 LPA in-hand salary: about ₹1,29,330 a month with PF on full basic, or ₹1,44,025 with PF capped at ₹1,800.
- Tax is ₹1,57,435 a year including cess, because taxable income of ₹17,56,900 sits in the 20% slab.
- Employer NPS at 14% of basic lowers tax to ₹1,05,596 and adds ₹1.4 lakh a year to your retirement savings.
- The old regime wins at 20 LPA only if you claim almost every deduction, including a home loan.
- About 78% of a 20 LPA CTC reaches your bank account each year.
20 LPA in-hand salary: full calculation
We assume basic pay is 50% of CTC (the norm under the new labour codes), PF is 12% of full basic on both sides, gratuity is 4.81% of basic and professional tax is ₹2,500 a year. These are the same assumptions we use in our 15 LPA and 10 LPA breakups, so you can compare them directly.
| Step | Amount (yearly) |
|---|---|
| CTC | ₹20,00,000 |
| Less: employer PF (12% of basic) | ₹1,20,000 |
| Less: gratuity (4.81% of basic) | ₹48,100 |
| = Gross salary | ₹18,31,900 |
| Less: your PF (12% of basic) | ₹1,20,000 |
| Less: professional tax | ₹2,500 |
| Less: income tax (new regime) | ₹1,57,435 |
| = In-hand salary (yearly) | ₹15,51,965 |
| In-hand per month | ₹1,29,330 |
- Employer PF (₹1,20,000) and your PF (₹1,20,000): together ₹2.4 lakh a year goes into your EPF, earning 8.25% (FY 2025-26 rate). It is your money, just not in your hand today.
- Gratuity (₹48,100): paid only when you leave after five years of service.
- Professional tax (₹2,500): nil in Delhi, Haryana and Uttar Pradesh, so take-home there is about ₹208 a month higher.
- Income tax (₹1,57,435): worked out slab by slab below.
How much tax on 20 LPA? Slab-by-slab working
Your gross salary of ₹18,31,900 becomes ₹17,56,900 after the ₹75,000 standard deduction. That is well above the ₹12 lakh rebate limit, so every slab from ₹4 lakh upwards is taxed:
| Slab (taxable income) | Rate | Tax |
|---|---|---|
| Up to ₹4,00,000 | Nil | ₹0 |
| ₹4,00,001 – ₹8,00,000 | 5% | ₹20,000 |
| ₹8,00,001 – ₹12,00,000 | 10% | ₹40,000 |
| ₹12,00,001 – ₹16,00,000 | 15% | ₹60,000 |
| ₹16,00,001 – ₹17,56,900 | 20% | ₹31,380 |
| Tax before cess | ₹1,51,380 | |
| Add: 4% cess | ₹6,055 | |
| Total tax | ₹1,57,435 |
Your effective tax rate is about 8.6% of gross salary, even though your top slab is 20%. Each extra ₹1 lakh of taxable income now costs you ₹20,800 in tax, which is why the NPS and PF choices below matter more at 20 LPA than at 12 or 15 LPA.
Monthly payslip for 20 LPA
| Payslip line | Monthly amount |
|---|---|
| Basic pay | ₹83,333 |
| House rent allowance (HRA) | ₹41,667 |
| Special allowance | ₹27,658 |
| Gross monthly pay | ₹1,52,658 |
| Less: employee PF | ₹10,000 |
| Less: TDS (income tax) | ₹13,120 |
| Less: professional tax | ₹208 |
| Net pay | ₹1,29,330 |
Some months may look different. Bonuses, arrears and one-time payouts are added to the month they are paid, and employers often adjust TDS in the last quarter to match your actual yearly tax.
How to cut tax on 20 LPA (legally)
The new regime allows very few deductions, but the biggest one is still open: your employer’s contribution to NPS, up to 14% of basic. At 20 LPA that is ₹1,40,000 a year, which pulls taxable income down to ₹14,76,900.
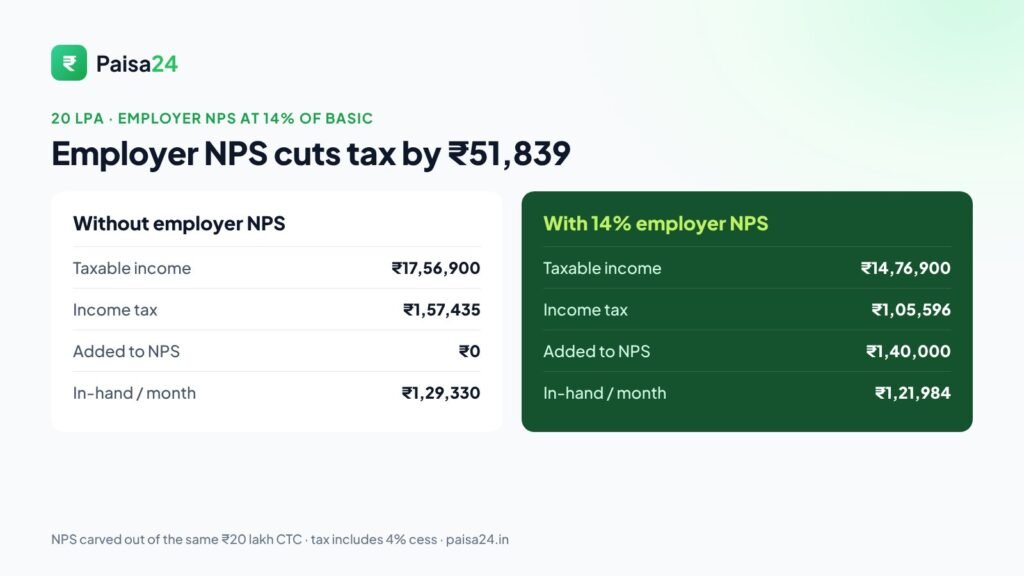
| Without employer NPS | With 14% employer NPS | |
|---|---|---|
| Taxable income | ₹17,56,900 | ₹14,76,900 |
| Income tax | ₹1,57,435 | ₹1,05,596 |
| Added to NPS each year | ₹0 | ₹1,40,000 |
| In-hand per month | ₹1,29,330 | ₹1,21,984 |
You get about ₹7,346 less cash each month, but you save ₹51,839 of tax and build ₹1.4 lakh of retirement savings every year. NPS money is locked until 60, with partial withdrawals allowed for specific needs, so use it only if you are comfortable with that lock-in. Ask HR whether your company offers a corporate NPS option.
Tip: Other new-regime-friendly perks include company-leased cars, meal cards within limits and reimbursements for phone, internet and books. Each one moves part of your CTC out of taxable salary.
In-hand salary under different structures
| Structure | Gross salary | Income tax | In-hand per month |
|---|---|---|---|
| 50% basic, PF on full basic | ₹18,31,900 | ₹1,57,435 | ₹1,29,330 |
| 40% basic, PF on full basic | ₹18,65,520 | ₹1,64,428 | ₹1,33,549 |
| 50% basic, PF capped at ₹1,800/month | ₹19,30,300 | ₹1,77,902 | ₹1,44,025 |
Capped PF gives you nearly ₹15,000 more a month, but your tax rises by about ₹20,500 a year and your EPF grows far more slowly. If you have no other disciplined savings, full-basic PF is the safer default.
New vs old regime at 20 LPA
| Old regime deductions | Old regime tax | New regime tax | Better choice |
|---|---|---|---|
| 80C ₹1.5 lakh + 80D ₹25,000 | ₹3,06,353 | ₹1,57,435 | New |
| Above + HRA exemption ₹2.6 lakh (rent ₹30,000/month, metro) | ₹2,25,233 | ₹1,57,435 | New |
| Above + NPS ₹50,000 + home loan interest ₹2 lakh | ₹1,47,233 | ₹1,57,435 | Old (by ₹10,202) |
Even with high metro rent, a home loan, full 80C, 80D and extra NPS, the old regime saves only about ₹10,000 at 20 LPA. For most people the new regime is simpler and cheaper. Read our new vs old tax regime guide to find your own break-even point.
In-hand salary for other CTCs (FY 2026-27)
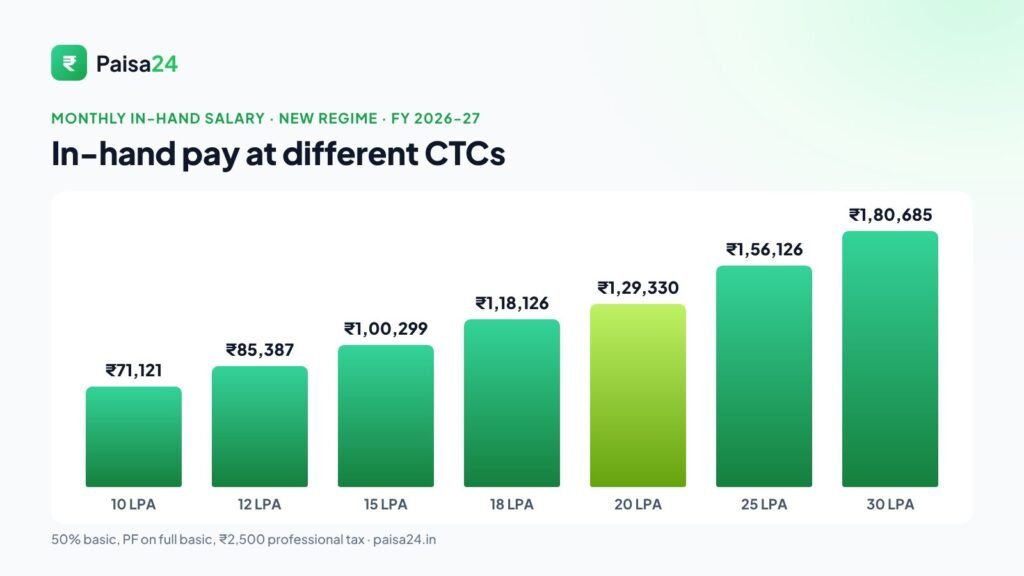
| CTC | In-hand per month | Income tax a year | In-hand as % of CTC |
|---|---|---|---|
| ₹10 lakh | ₹71,121 | ₹0 | 85% |
| ₹12 lakh | ₹85,387 | ₹0 | 85% |
| ₹15 lakh | ₹1,00,299 | ₹77,832 | 80% |
| ₹18 lakh | ₹1,18,126 | ₹1,20,699 | 79% |
| ₹20 lakh | ₹1,29,330 | ₹1,57,435 | 78% |
| ₹25 lakh | ₹1,56,126 | ₹2,63,868 | 75% |
| ₹30 lakh | ₹1,80,685 | ₹3,97,129 | 72% |
How to budget ₹1.29 lakh a month
With the 50/30/20 rule, ₹1,29,330 splits into about ₹64,665 for needs, ₹38,799 for wants and ₹25,866 for savings. Invested in an equity SIP at an assumed 12% a year, ₹25,866 a month could grow to about ₹60.1 lakh in 10 years and ₹2.58 crore in 20 years. Your EPF adds another ₹2.4 lakh a year on top. See how much SIP you need for ₹1 crore.
Watch out: At 20 LPA many people take a large home or car loan in the first year. Keep total EMIs under 40% of take-home, about ₹52,000 a month, so a job change or medical bill does not push you into debt.
How to increase your take-home pay
- Ask for employer NPS of up to 14% of basic. At 20 LPA it saves about ₹52,000 of tax a year.
- Choose your regime in April so TDS is right from the first month.
- Claim reimbursements such as phone, internet, books and fuel if your employer offers them.
- Check the PF basis if you need more monthly cash for a short period.
- Compare fixed pay, not CTC, when you switch jobs, because variable pay and joining bonuses inflate CTC.
How we calculated this: FY 2026-27 new regime slabs, ₹75,000 standard deduction, rebate up to ₹12 lakh of taxable income, 4% cess, 50% basic, PF at 12% on both sides, gratuity at 4.81% of basic and ₹2,500 professional tax. Employer NPS deduction is capped at 14% of basic in the new regime. No surcharge applies below ₹50 lakh of income. Your exact figure depends on your salary structure and state.
Frequently asked questions
What is the in-hand salary for 20 LPA?
About ₹1,29,330 a month in the new regime with 50% basic and PF on full basic. With PF capped at ₹1,800 a month it is about ₹1,44,025.
How much tax do I pay on 20 LPA?
About ₹1,57,435 a year including 4% cess in the new regime for FY 2026-27, or roughly ₹13,120 a month as TDS.
How can I save tax on 20 LPA in the new regime?
Ask your employer to put up to 14% of basic into NPS. At 20 LPA that is ₹1.4 lakh a year and cuts tax to about ₹1,05,596.
Is the new or old regime better for 20 LPA?
The new regime is better for most people. The old regime wins only with large deductions such as metro rent, a home loan, full 80C, 80D and extra NPS, and even then by about ₹10,000.
What is 20 LPA per month before deductions?
₹20 lakh divided by 12 is ₹1,66,667, but that includes employer PF and gratuity. Your gross monthly pay is about ₹1,52,658.
What percentage of 20 LPA is in-hand?
About 78% of CTC reaches your bank account in the new regime with PF on full basic.
Does professional tax apply everywhere?
No. States such as Delhi, Haryana and Uttar Pradesh do not levy it. Most others charge up to ₹2,500 a year.
Related guides and calculators
- EMI for ₹50 lakh home loan
- 15 LPA in-hand salary: monthly take-home
- 10 LPA in-hand salary: monthly take-home
- CTC vs in-hand salary explained
- Income tax slabs FY 2026-27
- Salary in-hand calculator
Sources: Income Tax Department · EPFO · PFRDA (NPS). Last checked 28 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.