EMI for ₹50 Lakh Home Loan: 10, 15, 20, 25 & 30 Years (2026)
The EMI for a ₹50 lakh home loan is about ₹41,822 a month for 20 years at 8%. See EMIs for every tenure and rate, salary needed and how to save interest.
On this page 9 sections
- 01₹50 lakh home loan EMI table (by rate and tenure)
- 02Total interest on a ₹50 lakh home loan
- 03Interest vs principal: where your EMI goes
- 04Salary needed for a ₹50 lakh home loan
- 05Down payment and extra costs
- 06Tax benefits on a ₹50 lakh home loan
- 07How to save ₹17 lakh+ on a ₹50 lakh loan
- 08Frequently asked questions
- 09Related guides and calculators
The EMI for a ₹50 lakh home loan is about ₹41,822 a month for 20 years at 8% interest. Stretch it to 30 years and the EMI falls to ₹36,688, but you pay about ₹82 lakh in interest, far more than the loan itself. Below are EMI tables for every common tenure and rate in October 2026, the salary you need, the down payment, the tax benefits and two simple ways to save over ₹17 lakh.
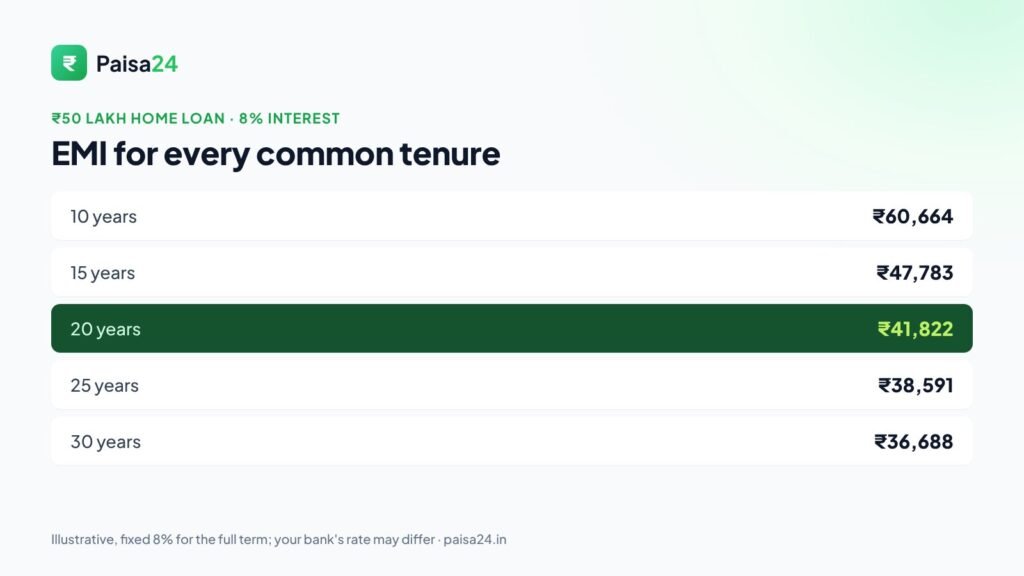
Quick answer: ₹50 lakh home loan EMI at 8%: ₹60,664 (10 years), ₹47,783 (15 years), ₹41,822 (20 years), ₹38,591 (25 years) and ₹36,688 (30 years).
Key takeaways
- ₹50 lakh for 20 years at 8%: EMI about ₹41,822, total interest about ₹50.37 lakh.
- Every ₹1 lakh of loan costs about ₹836 a month in EMI for 20 years at 8%.
- You need a take-home pay of about ₹84,000 a month for banks to approve a 20-year ₹50 lakh loan.
- Raising your EMI by 5% a year saves about ₹17.7 lakh and closes the loan nearly 8 years early.
- Because the loan is above ₹30 lakh, banks fund at most 80% of the property value, so plan at least ₹12.5 lakh as down payment.
₹50 lakh home loan EMI table (by rate and tenure)
Home loan rates start around 7.5% after the October 2026 repo rate hike to 5.50%, and most salaried borrowers pay between 7.5% and 9% depending on their credit score and lender. Here is the monthly EMI for each combination:
| Rate | 10 years | 15 years | 20 years | 25 years | 30 years |
|---|---|---|---|---|---|
| 7.5% | ₹59,351 | ₹46,351 | ₹40,280 | ₹36,950 | ₹34,961 |
| 8% | ₹60,664 | ₹47,783 | ₹41,822 | ₹38,591 | ₹36,688 |
| 8.5% | ₹61,993 | ₹49,237 | ₹43,391 | ₹40,261 | ₹38,446 |
| 9% | ₹63,338 | ₹50,713 | ₹44,986 | ₹41,960 | ₹40,231 |
A 1% difference in rate changes the 20-year EMI by about ₹3,200 a month and total interest by nearly ₹7.6 lakh. That is why a good CIBIL score (750 or more) is worth more than any festive offer.
Free calculatorCalculate the EMI for your loan amountHome, car & personal loan EMI with a full schedule.Total interest on a ₹50 lakh home loan
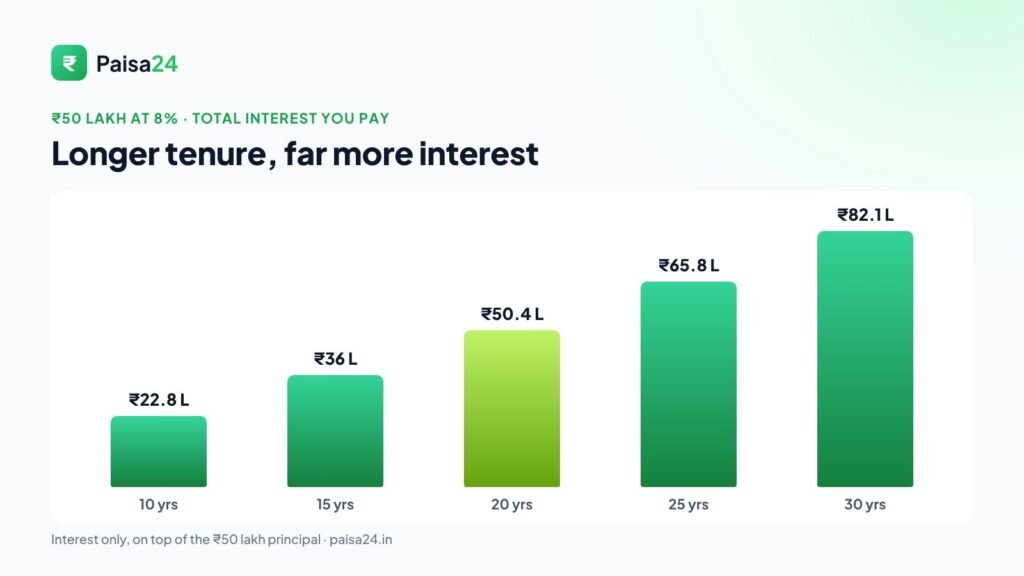
| Tenure | EMI at 8% | Total interest | Total paid |
|---|---|---|---|
| 10 years | ₹60,664 | ₹22.80 lakh | ₹72.80 lakh |
| 15 years | ₹47,783 | ₹36.01 lakh | ₹86.01 lakh |
| 20 years | ₹41,822 | ₹50.37 lakh | ₹1.00 crore |
| 25 years | ₹38,591 | ₹65.77 lakh | ₹1.16 crore |
| 30 years | ₹36,688 | ₹82.08 lakh | ₹1.32 crore |
Going from 20 to 30 years lowers the EMI by only ₹5,134 a month but adds about ₹31.7 lakh of interest. A longer tenure is useful for approval, but plan to prepay so you do not actually take 30 years.
Interest vs principal: where your EMI goes
In the early years most of your EMI is interest. On a 20-year loan at 8%, the first year’s EMIs of about ₹5.02 lakh include roughly ₹3.96 lakh of interest and only ₹1.06 lakh of principal. Principal overtakes interest only in year 12. By year 20 almost the whole EMI goes to principal.
| Loan year | Interest paid | Principal repaid |
|---|---|---|
| Year 1 | ₹3,96,181 | ₹1,05,683 |
| Year 10 | ₹2,85,263 | ₹2,16,601 |
| Year 20 | ₹21,087 | ₹4,80,777 |
This is why prepayments in the first 5 to 7 years save the most interest. Read our guide on whether to reduce EMI or tenure when you prepay.
Salary needed for a ₹50 lakh home loan
Most banks want your total EMIs to stay within 40% to 50% of take-home pay (the FOIR rule). For a ₹41,822 EMI that means a net monthly salary of about ₹84,000 at 50% or ₹1,04,600 at 40%, if you have no other loans.
| Tenure (8%) | EMI | Take-home needed (50% FOIR) | Take-home needed (40% FOIR) |
|---|---|---|---|
| 15 years | ₹47,783 | ₹95,566 | ₹1,19,458 |
| 20 years | ₹41,822 | ₹83,644 | ₹1,04,555 |
| 25 years | ₹38,591 | ₹77,182 | ₹96,478 |
| 30 years | ₹36,688 | ₹73,376 | ₹91,720 |
A take-home of about ₹84,000 matches a CTC of roughly ₹12 lakh in the new regime. See our 15 LPA in-hand salary breakup for exact monthly figures, or add a co-applicant’s income to qualify for a larger amount.
Free calculatorCheck how big a home loan your salary getsHow big a home loan your salary can get you.Down payment and extra costs
RBI rules let banks lend up to 80% of the property value for loans between ₹30 lakh and ₹75 lakh. So a ₹50 lakh loan needs a property worth at least ₹62.5 lakh and a down payment of at least ₹12.5 lakh. On top of that, budget for:
- Stamp duty and registration: usually 5% to 8% of the property value, depending on your state (about ₹3 lakh to ₹5 lakh here). Banks do not fund this.
- Processing fee: typically 0.25% to 1% of the loan plus GST.
- Legal, valuation and insurance costs: a few thousand rupees each; home loan insurance is optional.
Tax benefits on a ₹50 lakh home loan
In the old regime, a self-occupied home lets you deduct up to ₹2 lakh of interest a year and up to ₹1.5 lakh of principal under 80C. In year 1 your interest is about ₹3.96 lakh, so you can claim the full ₹2 lakh. In the new regime, there is no deduction for a self-occupied home loan. Compare both in our new vs old regime guide.
How to save ₹17 lakh+ on a ₹50 lakh loan
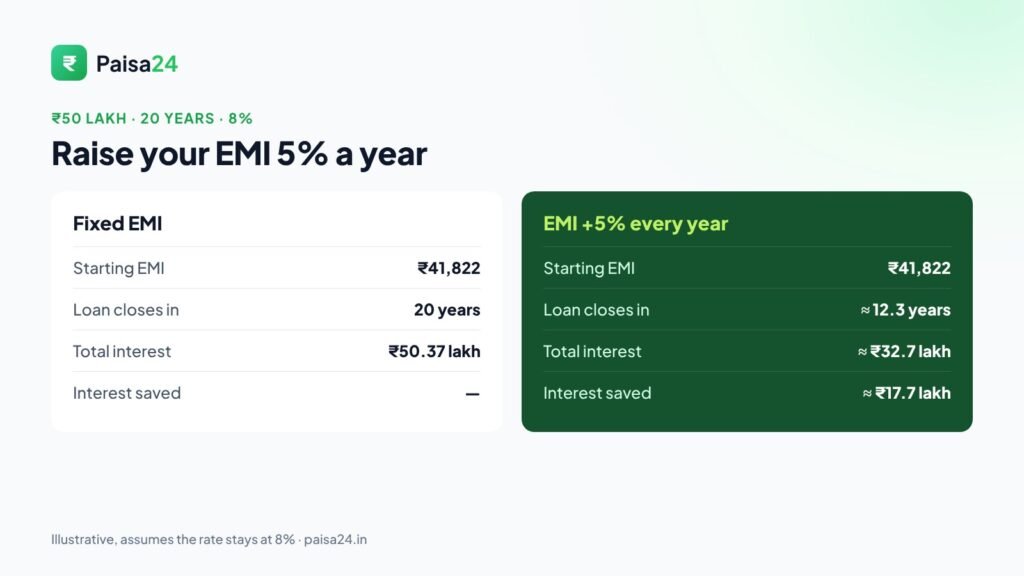
| Strategy (20 years, 8%) | Loan closes in | Interest saved |
|---|---|---|
| Pay the fixed EMI only | 20 years | — |
| Prepay ₹1 lakh every year | 14 years | about ₹17.0 lakh |
| Raise EMI by 5% every year | about 12.3 years | about ₹17.7 lakh |
- Step up your EMI with your increment. A 5% yearly increase is easy to absorb and has the biggest effect.
- Prepay from bonuses in the first 7 years, when interest is highest. Floating-rate home loans for individuals have no prepayment penalty.
- Ask for a rate review when your CIBIL score improves, or move the loan to another lender if the gap is 0.5% or more.
- Choose a tenure you can shorten. Take 25 to 30 years for comfort, then prepay as if it were 15 to 20.
Tip: When the repo rate rises, banks usually extend your tenure instead of raising the EMI. Ask your bank to raise the EMI instead, so your loan does not quietly stretch by several years.
Frequently asked questions
What is the EMI for a ₹50 lakh home loan for 20 years?
About ₹41,822 a month at 8%, ₹40,280 at 7.5% and ₹44,986 at 9%.
What is the EMI for ₹50 lakh for 30 years?
About ₹36,688 a month at 8%. Total interest over 30 years is about ₹82 lakh.
What salary is needed for a ₹50 lakh home loan?
About ₹84,000 a month take-home for a 20-year loan at 8%, if you have no other EMIs and the bank allows 50% FOIR.
How much down payment do I need for a ₹50 lakh loan?
At least ₹12.5 lakh, because banks can fund only 80% of a property worth ₹62.5 lakh, plus stamp duty and registration.
How much total interest will I pay on ₹50 lakh?
About ₹50.37 lakh over 20 years at 8%, ₹36 lakh over 15 years and ₹82 lakh over 30 years.
Can I close a ₹50 lakh home loan early?
Yes. Floating-rate home loans for individuals have no prepayment or foreclosure charges, so you can prepay any time.
Related guides and calculators
- 20 LPA in-hand salary: monthly take-home
- EMI for ₹30 lakh home loan
- Home loan prepayment: reduce EMI or tenure?
- How to improve your CIBIL score
- EMI calculator
- Home loan eligibility calculator
Sources: RBI · National Housing Bank · Income Tax Department. Last checked 28 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.