2000 SIP for 25 Years: What You Really Get After Inflation
2000 SIP for 25 years grows to ₹37.95 lakh at 12%, but only about ₹8.84 lakh in today's money. See the inflation-adjusted table and how to close the gap.
On this page 9 sections
- 012000 SIP for 25 years: future value at 10%, 12% and 14%
- 02What a 2000 SIP for 25 years is really worth after inflation
- 032000 SIP for 25 years: nominal vs real value, year by year
- 04Why a 2000 SIP for 25 years needs a yearly step-up
- 05How much SIP do you need for a goal in today’s money?
- 06Tax on SIP gains
- 07How to start a 2000 SIP for 25 years
- 08Frequently asked questions
- 09Related guides
A 2000 SIP for 25 years grows to about ₹37.95 lakh at a 12% annual return, on a total investment of just ₹6 lakh. But that figure is in future rupees. After 6% yearly inflation, it buys only what about ₹8.84 lakh buys today. This guide shows the real, inflation-adjusted value of a ₹2,000 monthly SIP, why the gap is so large and how to close it. For the plain returns table at 10, 15, 20 and 30 years, see our SIP of ₹2,000 guide.
Quick answer: A ₹2,000 SIP for 25 years at 12% becomes ₹37.95 lakh in future rupees, or about ₹8.84 lakh in today’s money at 6% inflation.
Key takeaways
- You invest ₹6 lakh over 25 years (₹2,000 × 300 months). At 12% it grows to about ₹37.95 lakh.
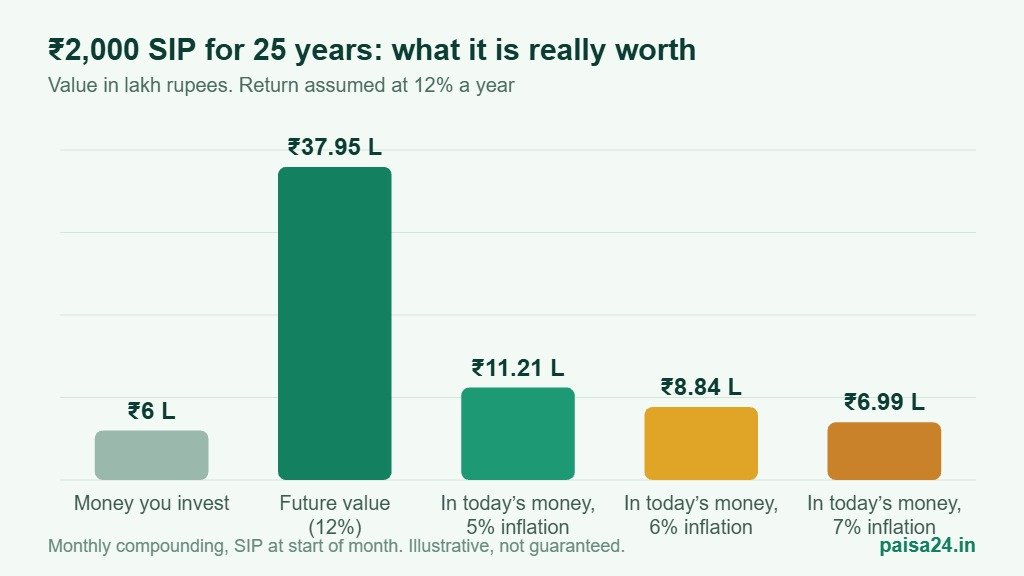
- At 6% inflation, ₹37.95 lakh is worth about ₹8.84 lakh in today’s money. At 5% it is ₹11.21 lakh and at 7% it is ₹6.99 lakh.
- Prices rise about 4.3 times in 25 years at 6% inflation, so ₹2,000 a month in year 25 buys what ₹466 buys today.
- A ₹2,000 flat SIP will not reach ₹50 lakh in today’s money. You need about ₹11,300 a month, or a ₹5,000 start with a 10% yearly step-up.
- Raising the SIP by 10% every year turns ₹37.95 lakh into about ₹85.51 lakh (₹19.92 lakh in today’s money).
2000 SIP for 25 years: future value at 10%, 12% and 14%
With 300 monthly instalments of ₹2,000, you invest ₹6 lakh in total. What it grows to depends on the return you earn. Equity funds have no guaranteed return, and 12% is only a common planning assumption.
| Return a year | Total invested | Future value | Gain | Money multiple |
|---|---|---|---|---|
| 10% | ₹6 lakh | ₹26.76 lakh | ₹20.76 lakh | 4.5x |
| 12% | ₹6 lakh | ₹37.95 lakh | ₹31.95 lakh | 6.3x |
| 14% | ₹6 lakh | ₹54.55 lakh | ₹48.55 lakh | 9.1x |
What a 2000 SIP for 25 years is really worth after inflation
Inflation shrinks what each rupee can buy, so a 2000 SIP for 25 years is worth less than it looks. At 6% a year, prices rise about 4.3 times in 25 years. Divide the future value by that multiple to see its worth in today’s money.
| Yearly inflation | Prices rise by | ₹37.95 lakh in today’s money |
|---|---|---|
| 5% | 3.39x | ₹11.21 lakh |
| 6% | 4.29x | ₹8.84 lakh |
| 7% | 5.43x | ₹6.99 lakh |
Watch out: 6% is a cautious planning figure, above the RBI’s 4% inflation target. Your own inflation may be higher or lower, but it is never zero. Judge any long SIP by its inflation-adjusted value, not just the headline number.
2000 SIP for 25 years: nominal vs real value, year by year
| Year | You invest | Future value at 12% | Worth in today’s money (6% inflation) |
|---|---|---|---|
| 10 | ₹2.4 lakh | ₹4.65 lakh | ₹2.59 lakh |
| 15 | ₹3.6 lakh | ₹10.09 lakh | ₹4.21 lakh |
| 20 | ₹4.8 lakh | ₹19.98 lakh | ₹6.23 lakh |
| 25 | ₹6 lakh | ₹37.95 lakh | ₹8.84 lakh |
Even in today’s money, a 2000 SIP for 25 years more than doubles your ₹6 lakh. The real return is about 5.7% a year (12% minus 6% inflation, compounded). So the SIP does beat inflation. The issue is that ₹2,000 is a small amount to start with.
Why a 2000 SIP for 25 years needs a yearly step-up
The ₹2,000 in a 2000 SIP for 25 years loses buying power too. After 25 years at 6% inflation, ₹2,000 a month buys only what about ₹466 buys today. A yearly step-up keeps your investment in line with your income and with prices.
| Yearly step-up | Total invested | Future value at 12% | In today’s money (6% inflation) |
|---|---|---|---|
| None | ₹6 lakh | ₹37.95 lakh | ₹8.84 lakh |
| 5% | ₹11.45 lakh | ₹54.70 lakh | ₹12.74 lakh |
| 10% | ₹23.60 lakh | ₹85.51 lakh | ₹19.92 lakh |
Tip: Most fund houses and investment apps let you set an automatic yearly top-up when you start the SIP. Turn it on once and it runs by itself. Our ₹2,000 SIP guide also shows a 20-year step-up case.
How much SIP do you need for a goal in today’s money?
Fix your goal in today’s rupees, inflate it to 25 years from now at 6%, then find the SIP that reaches it at 12%.
| Goal in today’s money | Needed after 25 years | Flat monthly SIP | Starting SIP with 10% yearly step-up |
|---|---|---|---|
| ₹25 lakh | ₹1.07 crore | ₹5,654 | ₹2,510 |
| ₹50 lakh | ₹2.15 crore | ₹11,308 | ₹5,019 |
| ₹1 crore | ₹4.29 crore | ₹22,617 | ₹10,038 |
So a 2000 SIP for 25 years is a good start, but on its own it will not reach ₹50 lakh in today’s money. Treat it as your first step and raise it with every pay rise. If you want to aim at ₹1 crore, read our SIP for ₹1 crore guide.
Tax on SIP gains
Gains on equity funds held for more than a year are long-term capital gains. Under the current rules, long-term gains above ₹1.25 lakh in a financial year are taxed at 12.5%. Rules can change, so check with the Income Tax Department or a tax professional for your case.
How to start a 2000 SIP for 25 years
- Complete your KYC with PAN and Aadhaar on any fund house website or investment app.
- Pick one diversified fund, such as a Nifty 50 index fund or a flexi-cap fund, in the direct plan. See direct vs regular plans for the cost difference.
- Set the SIP date a day or two after your salary arrives, and switch on the yearly step-up.
- Review once a year. Do not stop the SIP in a market fall; that is when the units are cheapest.
Frequently asked questions
How much will a 2000 SIP be in 25 years?
About ₹37.95 lakh at 12%, ₹26.76 lakh at 10% and ₹54.55 lakh at 14%, on a total investment of ₹6 lakh.
What is ₹37.95 lakh worth in today’s money?
About ₹8.84 lakh at 6% inflation, ₹11.21 lakh at 5% and ₹6.99 lakh at 7%.
Is a 2000 SIP for 25 years enough for retirement?
On its own, no. In today’s money it is under ₹9 lakh at 6% inflation. It is a strong habit to start with, but you should raise the amount every year.
Can I increase my SIP later?
Yes. You can set a yearly step-up when you start, or add a second SIP later when your income grows.
Which fund is best for a ₹2,000 SIP?
There is no single best fund. Many beginners use a diversified Nifty 50 index fund or a flexi-cap fund in the direct plan. This is general information, not advice.
Related guides
- SIP of ₹2,000: returns for 10 to 30 years
- How to build ₹1 crore with a SIP
- How to calculate SIP returns yourself
- XIRR vs CAGR for SIP returns
Sources: AMFI · RBI (inflation target) · Income Tax Department. Last checked 18 November 2026. Figures assume monthly compounding with the SIP paid at the start of each month. They are illustrative estimates, not tax or financial advice. How we research and fact-check.
Keep exploring on Paisa24
🧮 Free calculators for this topic
- SIP Calculator — test your own amount, return and tenor
- FD vs SIP Calculator — compare safe vs market returns
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.
More from Investing.
 Fixed DepositsAU Small Finance Bank FD Rates 2026: Up to 7.40%, Senior Citizens Get 7.90%
 StocksNvidia Stock Crash: $1.6 Trillion Wiped Out. What It Means for Indian Investors and India’s AI Mission
 InvestingHow to Invest in Silver in India (2026): ETF vs FoF vs Coins vs Digital Silver After the 50% Crash