How to Calculate SIP Returns Yourself: Formula, Example and Excel (2026)
The exact SIP formula, a worked ₹5,000 a month example, the Excel shortcut and the 3 mistakes that make most SIP estimates wrong.
On this page 9 sections
- 01How to calculate SIP returns: the formula in plain words
- 02How to calculate SIP returns: a worked example
- 03What ₹5,000 a month becomes over time
- 04How to calculate SIP returns in Excel or Google Sheets
- 053 mistakes people make when they calculate SIP returns
- 06Bonus: how to calculate a step-up SIP
- 07SIP vs lump sum: which gives more?
- 08The fastest way to calculate SIP returns: Paisa24 SIP calculator
- 09FAQs on how to calculate SIP returns
Want to know how to calculate SIP returns on your own, without trusting an app’s number blindly? It takes one formula, a phone calculator and about five minutes. In this guide, you will learn the exact SIP formula, work through a real example, check it in Excel, and see the three mistakes that make most people’s estimates wrong. Then you can verify everything in seconds with the free Paisa24 SIP calculator.
⚡ How to calculate SIP returns: quick answer
- Formula: FV = P × [(1 + i)n − 1] ÷ i × (1 + i)
- P = monthly SIP, i = annual return ÷ 12 ÷ 100, n = number of months.
- Example: ₹5,000 a month at 12% for 10 years grows to about ₹11.62 lakh on ₹6 lakh invested.
- Excel: =FV(12%/12, 120, -5000, 0, 1)
- Shortcut: Use the Paisa24 SIP calculator to get the same answer with a year-by-year table.
How to calculate SIP returns: the formula in plain words
First, remember that a SIP is simply a fixed amount you invest every month. Each instalment then grows for a different length of time. Your first ₹5,000 grows for the full period, while your last ₹5,000 grows for just one month. The SIP formula adds up all those instalments for you:
FV = P × [(1 + i)n − 1] ÷ i × (1 + i)
- FV is the future value, or what your SIP will be worth.
- P is your monthly SIP amount.
- i is the monthly rate of return. So 12% a year becomes 12 ÷ 12 ÷ 100 = 0.01.
- n is the total number of monthly instalments. So 10 years becomes 120.
The last part, × (1 + i), is there because SIP money goes in at the start of each month. Therefore it earns one extra month of growth. This is the same method most Indian SIP calculators, including ours, use.
How to calculate SIP returns: a worked example
To see how to calculate SIP returns in practice, let us take ₹5,000 a month, an expected return of 12% a year, for 10 years.
- Find i: 12 ÷ 12 ÷ 100 = 0.01
- Find n: 10 × 12 = 120
- Work out (1 + i)n: 1.01120 = about 3.3004
- Subtract 1 and divide by i: (3.3004 − 1) ÷ 0.01 = 230.04
- Multiply by (1 + i): 230.04 × 1.01 = 232.34
- Multiply by P: 232.34 × 5,000 = ₹11,61,695
So you invest ₹6,00,000, and your estimated gain is about ₹5,61,695. In other words, almost half of your final amount comes from compounding, not from your own pocket.
What ₹5,000 a month becomes over time
Next, here is the same SIP of ₹5,000 at 12%, worked out with the formula above for different time periods. Notice how the gain overtakes your investment as time passes.
| Period | You invest | Estimated value | Estimated gain |
|---|---|---|---|
| 5 years | ₹3,00,000 | ₹4,12,432 | ₹1,12,432 |
| 10 years | ₹6,00,000 | ₹11,61,695 | ₹5,61,695 |
| 15 years | ₹9,00,000 | ₹25,22,880 | ₹16,22,880 |
| 20 years | ₹12,00,000 | ₹49,95,740 | ₹37,95,740 |
Want your own numbers? Change the amount, rate or years in the Paisa24 SIP calculator, and it redraws this table and a growth chart instantly.
How to calculate SIP returns in Excel or Google Sheets
Of course, you do not need to do the powers by hand when you calculate SIP returns. Excel and Google Sheets have a built-in future value function. Type this into any cell:
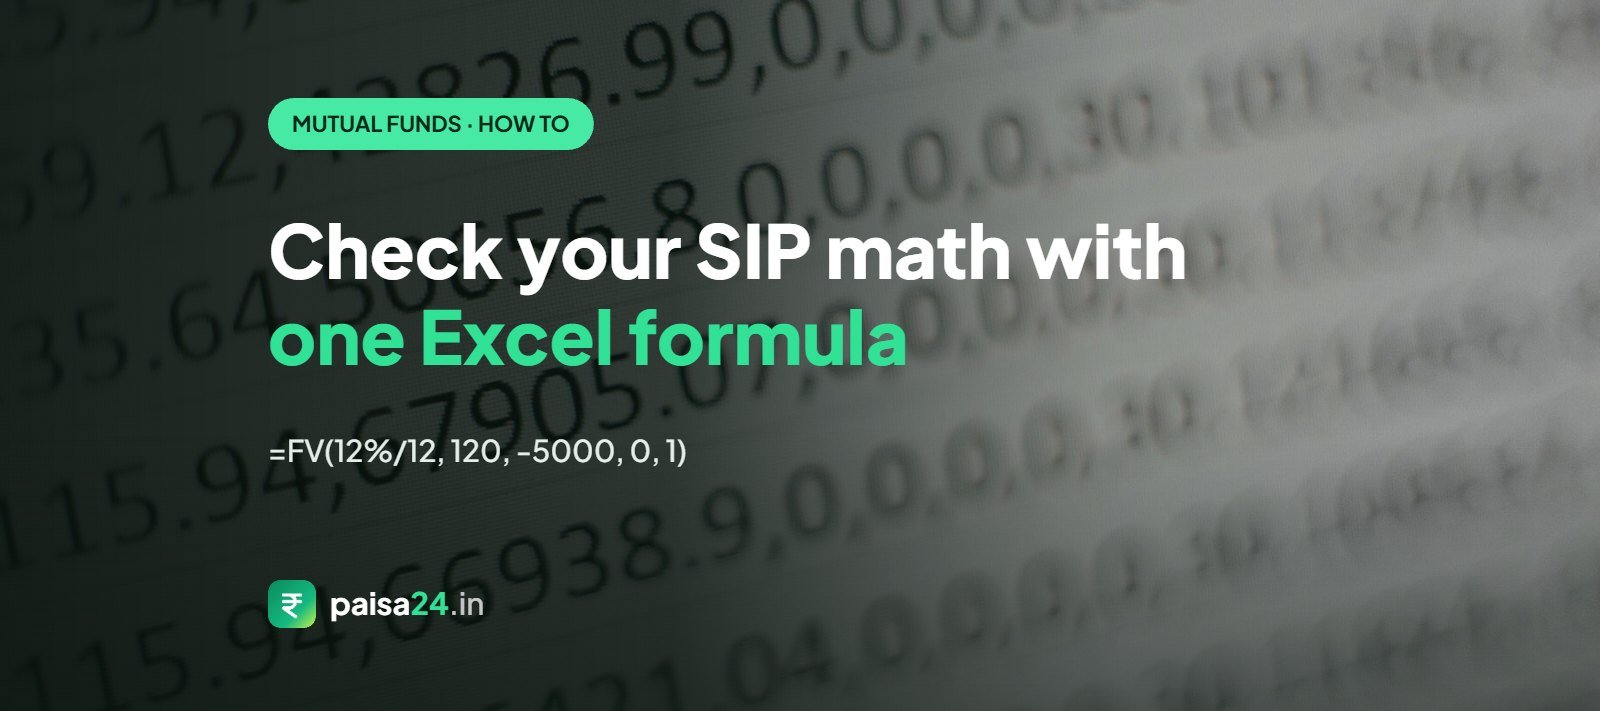
=FV(12%/12, 120, -5000, 0, 1)
- 12%/12 is the monthly rate.
- 120 is the number of months.
- -5000 is your SIP. It is negative because money leaves your pocket.
- 0 means you start with nothing.
- 1 tells Excel you invest at the start of each month.
As a result, you get ₹11,61,695, which matches our manual answer. However, if you leave out the last “1”, Excel assumes month-end investing and shows ₹11,50,193 instead. That small setting explains why two calculators sometimes disagree.
3 mistakes people make when they calculate SIP returns
1. Treating “12% return” as guaranteed
First of all, equity funds do not grow at a fixed rate. Some years give 25%, while others give −10%. Therefore, treat the formula as an estimate, and also test a cautious rate such as 10%.
2. Forgetting inflation
Similarly, ₹11.62 lakh in 10 years will not buy what ₹11.62 lakh buys today. At 6% inflation, it is worth about ₹6.49 lakh in today’s money. To find this, divide the future value by (1.06)10.
3. Ignoring tax and costs
Also, equity fund gains held for more than a year are taxed as long-term capital gains at 12.5% above ₹1.25 lakh a year under current rules. Also, regular plans charge a higher expense ratio than direct plans. See our guide on direct vs regular mutual funds to understand the cost difference.
Bonus: how to calculate a step-up SIP
Meanwhile, a step-up SIP raises your instalment every year, usually by 5–10%, in line with your salary. Because of this, the single formula above no longer works, because P changes each year. Instead, you calculate each year’s 12 instalments separately and add them up.
For example, start at ₹5,000 and raise it 10% every year, at 12% for 10 years. You invest about ₹9.56 lakh, and it grows to roughly ₹16.87 lakh. That is ₹5.25 lakh more than a flat SIP. Still, doing this by hand is slow, which is why our SIP calculator has a step-up option built in.
SIP vs lump sum: which gives more?
Now, once you know how to calculate SIP returns, compare a lump sum. If you invested the same ₹6 lakh as a lump sum on day one at 12%, it would grow to about ₹18.64 lakh in 10 years, because all the money compounds for the full period. However, most people do not have a big amount ready, and SIPs reduce the risk of investing everything at a market peak. Compare both side by side with the FD vs SIP calculator.
The fastest way to calculate SIP returns: Paisa24 SIP calculator
- Same formula, no guesswork: it uses the start-of-month method explained above.
- Step-up built in: add a yearly increase and see the difference instantly.
- Year-by-year table and chart: see exactly when your gains overtake your investment.
- Private and free: the maths runs on your device. No sign-up, no OTP, no sales call.
So, try it now: Paisa24 SIP calculator →
In addition, we explain money concepts like this in 60-second reels. Follow @paisa24_in on Instagram.
FAQs on how to calculate SIP returns
What is the formula to calculate SIP returns?
FV = P × [(1 + i)n − 1] ÷ i × (1 + i), where P is the monthly SIP, i is the monthly return rate and n is the number of months.
How much will ₹5,000 SIP give in 10 years?
At an assumed 12% a year, about ₹11.62 lakh on ₹6 lakh invested. At 10%, it would be about ₹10.3 lakh.
Why does my fund app show a different return?
That is because your app shows the actual return on actual dates, usually as XIRR. In contrast, the formula gives an estimate at a fixed rate. Read our guide on XIRR vs CAGR for SIP returns to understand the difference.
Figures are estimates at assumed rates and do not include taxes or fund costs. Mutual fund returns are not guaranteed. This is general information, not investment advice.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.