Salary Required for 50 Lakh Home Loan: Income Needed by Tenor (2026)
Salary required for 50 lakh home loan: about ₹87,000 to ₹1.08 lakh a month at 8.5% for 20 years. See income needed by tenor and rate, and how to qualify.
On this page 7 sections
- 01Salary required for 50 lakh home loan, by tenor
- 02How the rate changes the salary required for 50 lakh home loan
- 03What else lenders check besides salary
- 04Can you get a ₹50 lakh home loan on a lower salary?
- 05How to meet the salary required for 50 lakh home loan
- 06Frequently asked questions
- 07Related guides
The salary required for 50 lakh home loan is roughly ₹87,000 to ₹1.08 lakh a month for a 20-year loan at 8.5%, depending on how much of your income the lender lets you commit to EMIs. Longer tenors lower the income you need but add lakhs in interest. This guide shows the income needed by tenor and rate, what else banks check and how to qualify on a lower salary. To see the EMI alone, read our ₹50 lakh home loan EMI guide.
Quick answer: At 8.5% for 20 years, the EMI on ₹50 lakh is ₹43,391. Lenders commonly want total EMIs within about 40% to 50% of your net monthly income, so you need about ₹86,800 to ₹1.08 lakh a month.
Key takeaways
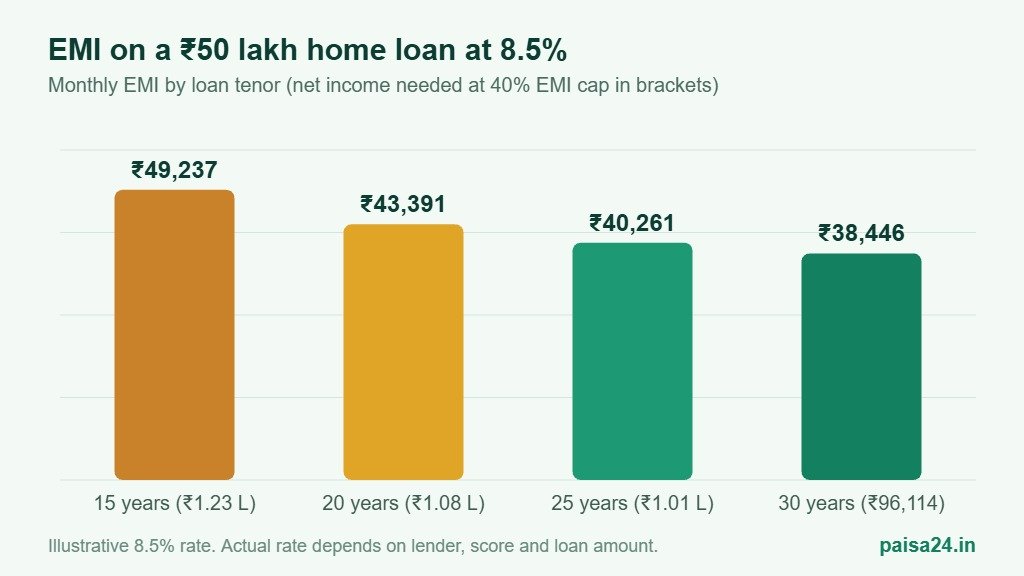
- EMI on ₹50 lakh at 8.5%: ₹49,237 (15 years), ₹43,391 (20 years), ₹40,261 (25 years) and ₹38,446 (30 years).
- Net income needed for a 20-year loan: about ₹86,782 at a 50% EMI cap and ₹1,08,478 at a 40% cap.
- Stretching from 20 to 30 years cuts the EMI by about ₹4,945 but adds about ₹34.3 lakh in interest.
- Your existing EMIs reduce eligibility rupee for rupee.
- Under RBI’s loan-to-value norms, a ₹30 to ₹75 lakh loan can fund up to 80% of the property value. So a ₹62.5 lakh property needs at least ₹12.5 lakh down payment, plus stamp duty and registration.
Salary required for 50 lakh home loan, by tenor
The salary required for 50 lakh home loan depends on your EMI-to-income ratio. Banks look at this ratio, often called FOIR. The exact cap depends on the lender and your income level. We show both 40% and 50% so you can see the range. All figures use an illustrative 8.5% interest rate.
| Tenor | Monthly EMI | Net income needed (50% cap) | Net income needed (40% cap) | Total interest |
|---|---|---|---|---|
| 15 years | ₹49,237 | ₹98,474 | ₹1,23,092 | ₹38.63 lakh |
| 20 years | ₹43,391 | ₹86,782 | ₹1,08,478 | ₹54.14 lakh |
| 25 years | ₹40,261 | ₹80,523 | ₹1,00,653 | ₹70.78 lakh |
| 30 years | ₹38,446 | ₹76,891 | ₹96,114 | ₹88.40 lakh |
The 40% column follows the rule in our 40% rule for EMI guide. It is the safer way to plan, because it leaves room for other expenses.
How the rate changes the salary required for 50 lakh home loan
| Interest rate (20 years) | Monthly EMI | Income needed (50% cap) | Income needed (40% cap) |
|---|---|---|---|
| 8.15% | ₹42,290 | ₹84,580 | ₹1,05,725 |
| 8.50% | ₹43,391 | ₹86,782 | ₹1,08,478 |
| 9.00% | ₹44,986 | ₹89,973 | ₹1,12,466 |
The RBI raised the repo rate to 5.50% on 7 October 2026, and forecasters expect more moves. A repo-linked loan can get costlier at reset, and a higher rate raises the income you need for a new loan. Read our RBI December policy preview and the repo rate hike explainer.
What else lenders check besides salary
- Existing EMIs. Car loans, personal loans and credit card dues count against your limit. With ₹1 lakh net income, a 50% cap and ₹10,000 of other EMIs, you have ₹40,000 left for the new EMI. That supports a loan of about ₹49.7 lakh over 25 years at 8.5%.
- Credit score. A CIBIL score of 750 or above generally helps with approval and a better rate. Check your CIBIL score for free before you apply.
- Age and tenor. Lenders usually want the loan to end by retirement age, so older applicants often get shorter tenors.
- Job and income stability. Salaried applicants are usually asked for recent salary slips and bank statements. Self-employed applicants are asked for income tax returns.
- Property value and down payment. RBI’s loan-to-value limits allow up to 90% for loans up to ₹30 lakh, 80% for ₹30 to ₹75 lakh and 75% above ₹75 lakh. For a ₹50 lakh loan at 80%, the property must be worth at least ₹62.5 lakh.
Can you get a ₹50 lakh home loan on a lower salary?
The salary required for 50 lakh home loan is higher than many expect. The table shows the loan your salary can support over 30 years at 8.5%, with a 50% EMI cap and no other EMIs.
| Net monthly salary | EMI room (50%) | Loan supported (30 years, 8.5%) |
|---|---|---|
| ₹50,000 | ₹25,000 | About ₹32.5 lakh |
| ₹60,000 | ₹30,000 | About ₹39.0 lakh |
| ₹80,000 | ₹40,000 | About ₹52.0 lakh |
| ₹1,00,000 | ₹50,000 | About ₹65.0 lakh |
If the salary required for 50 lakh home loan is out of reach, check what you can get today. At a stricter 40% cap, each loan amount is about 20% lower. These are rough estimates, not an offer. The lender’s own checks decide the final amount.
Watch out: A longer tenor is not free. Moving from 20 to 30 years cuts the EMI by about ₹4,945 but adds about ₹34.3 lakh in interest at 8.5%. Take the long tenor only if you plan to prepay when you can.
How to meet the salary required for 50 lakh home loan
- Add a co-applicant. A spouse or parent’s income is usually added to yours, which lifts the loan amount you can get.
- Clear other EMIs first. Closing a small personal loan frees up EMI room for the home loan.
- Raise your credit score. Pay dues on time and keep card usage low for a few months before applying.
- Increase the down payment. A smaller loan needs a smaller EMI and less income.
- Plan to prepay. If you take a long tenor now, part-prepay later. See whether to reduce EMI or tenure.
Tip: Use our home loan eligibility calculator to test your own income, existing EMIs and tenor before you visit a bank.
Frequently asked questions
What salary is required for a 50 lakh home loan?
About ₹87,000 to ₹1.08 lakh net a month for a 20-year loan at 8.5%, or about ₹77,000 to ₹96,000 for a 30-year loan. The exact figure depends on the lender, rate and your other EMIs.
Can I get a 50 lakh home loan on a 50,000 salary?
On your own income, a 30-year loan supports about ₹32.5 lakh at a 50% EMI cap. Adding a co-applicant’s income can raise the amount.
Do banks use gross or net salary?
Practice varies. Many lenders assess net (take-home) income, while some also look at gross pay and allowances. Ask your lender which one it uses.
What down payment is needed for a ₹50 lakh home loan?
At least about ₹12.5 lakh on a ₹62.5 lakh property under the 80% loan-to-value limit, plus stamp duty, registration and other charges.
Does a co-applicant improve eligibility?
Yes. The co-applicant’s income and credit profile are usually combined with yours, so the lender can approve a larger EMI.
Related guides
- EMI for ₹50 lakh home loan
- EMI for ₹40 lakh home loan
- How much EMI can you afford? The 40% rule
- Prepay home loan: reduce EMI or tenure
Sources: RBI (loan-to-value norms, repo rate) · TransUnion CIBIL. Last checked 18 November 2026. EMIs use an illustrative 8.5% rate unless stated. Lender rules differ, so confirm eligibility with your bank. Not financial advice. How we research and fact-check.
Keep exploring on Paisa24
🧮 Free calculators for this topic
- Home Loan Eligibility Calculator — see the loan your income supports
- EMI Calculator — check EMI for any amount and tenor
- Salary Calculator — find your take-home pay
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.