10 LPA In-Hand Salary: Monthly Take-Home After Tax (FY 2026-27)
10 LPA in-hand salary is about ₹71,121 a month in the new regime. See the full breakup of PF, gratuity, tax and take-home pay for FY 2026-27.
On this page 10 sections
- 0110 LPA in-hand salary: full calculation
- 02Why you pay zero income tax on 10 LPA
- 03Monthly payslip for 10 LPA
- 04In-hand salary under different salary structures
- 05New vs old regime at 10 LPA
- 06In-hand salary for other CTCs (FY 2026-27)
- 07How to budget ₹71,121 a month
- 08How to increase your take-home pay
- 09Frequently asked questions
- 10Related guides and calculators
On a 10 LPA salary, your in-hand pay is about ₹71,121 a month (₹8,53,450 a year) in the new tax regime for FY 2026-27. That assumes basic pay is 50% of CTC and PF is deducted on your full basic. If your employer caps PF at ₹1,800 a month, take-home rises to about ₹77,521. You pay zero income tax either way, thanks to the ₹12 lakh rebate.
Quick answer: 10 LPA in hand = ₹71,000 to ₹77,500 a month, depending on how your employer calculates PF. Income tax on 10 LPA is ₹0 in the new regime for FY 2026-27.
Key takeaways
- 10 LPA in-hand salary: about ₹71,121 a month with PF on full basic, or ₹77,521 with PF capped at ₹1,800.
- Income tax is zero: taxable income is ₹8,40,950, well under the ₹12 lakh rebate limit.
- About 15% of your CTC goes to PF, gratuity and professional tax, and most of it is still your money.
- The new regime beats the old regime at 10 LPA even if you pay rent and max out 80C.
10 LPA in-hand salary: full calculation
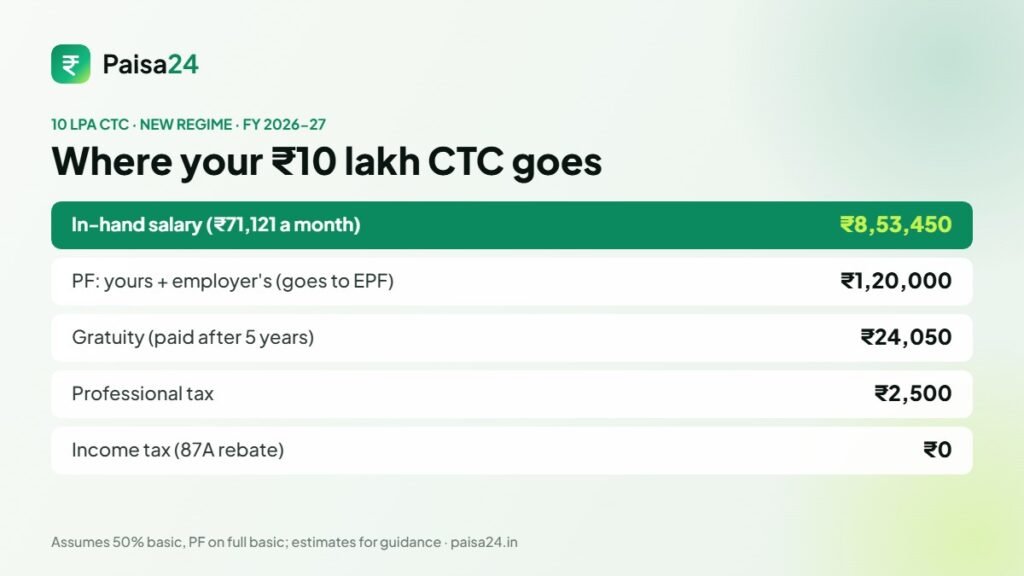
Most offer letters in 2026 set basic pay at 50% of CTC, because the new labour codes count anything above half of pay as wages for PF and gratuity. We use that structure, with PF at 12% of full basic, gratuity at 4.81% of basic and professional tax of ₹2,500 a year.
| Step | Amount (yearly) |
|---|---|
| CTC | ₹10,00,000 |
| Less: employer PF (12% of basic) | ₹60,000 |
| Less: gratuity (4.81% of basic) | ₹24,050 |
| = Gross salary | ₹9,15,950 |
| Less: your PF (12% of basic) | ₹60,000 |
| Less: professional tax | ₹2,500 |
| Less: income tax (new regime) | ₹0 |
| = In-hand salary (yearly) | ₹8,53,450 |
| In-hand per month | ₹71,121 |
Here is what each line means:
- Employer PF (₹60,000): your company pays 12% of your basic into your EPF account. It is part of your CTC, but you never see it in your salary. It earns 8.25% interest (the rate EPFO declared for FY 2025-26).
- Gratuity (₹24,050): many companies set aside 4.81% of basic for gratuity. You receive it only if you leave after five years of service.
- Your PF (₹60,000): another 12% of basic is cut from your pay and goes to the same EPF account. Together, ₹1,20,000 a year goes into your EPF.
- Professional tax (₹2,500): a state tax. It is zero in states such as Delhi, Haryana and Uttar Pradesh.
- Income tax (₹0): explained in the next section.
Why you pay zero income tax on 10 LPA
Under the new regime for FY 2026-27, the first ₹4 lakh of taxable income is tax-free, and a rebate wipes out the tax completely if taxable income stays at or below ₹12 lakh. Here is the working for 10 LPA:
| Item | Amount |
|---|---|
| Gross salary | ₹9,15,950 |
| Less: standard deduction | ₹75,000 |
| = Taxable income | ₹8,40,950 |
| Tax before rebate (5% on ₹4–8 lakh, 10% on the rest) | ₹24,095 |
| Less: rebate (taxable income below ₹12 lakh) | ₹24,095 |
| Income tax payable | ₹0 |
In fact, a salaried person pays no tax in the new regime until gross salary crosses about ₹12.75 lakh. So at 10 LPA you have plenty of room, even after a raise.
Monthly payslip for 10 LPA
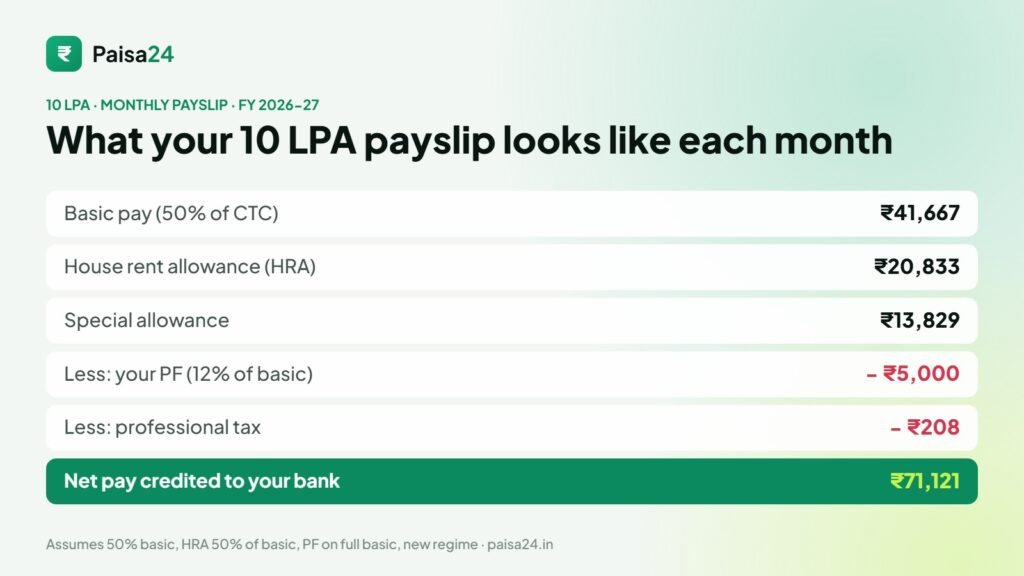
Your payslip shows the same numbers month by month. With HRA at 50% of basic (common in metros), a 10 LPA payslip typically looks like this:
| Payslip line | Monthly amount |
|---|---|
| Basic pay | ₹41,667 |
| House rent allowance (HRA) | ₹20,833 |
| Special allowance | ₹13,829 |
| Gross monthly pay | ₹76,329 |
| Less: employee PF | ₹5,000 |
| Less: professional tax | ₹208 |
| Less: TDS (income tax) | ₹0 |
| Net pay | ₹71,121 |
Tip: Some states collect professional tax unevenly, for example ₹200 a month and ₹300 in February. So your net pay can differ by ₹100 in one month. That is normal.
In-hand salary under different salary structures
Two people with the same 10 LPA CTC can take home different amounts. The biggest swing comes from how PF is calculated:
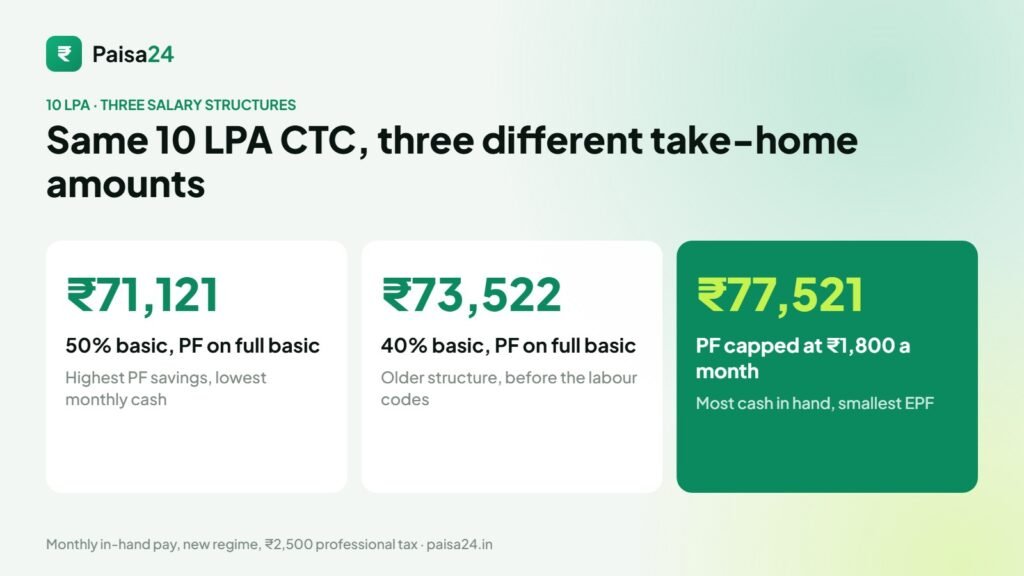
| Structure | Gross salary | Your PF a year | In-hand per month |
|---|---|---|---|
| 50% basic, PF on full basic | ₹9,15,950 | ₹60,000 | ₹71,121 |
| 40% basic, PF on full basic | ₹9,32,760 | ₹48,000 | ₹73,522 |
| 50% basic, PF capped at ₹1,800/month | ₹9,54,350 | ₹21,600 | ₹77,521 |
Should you ask for PF to be capped?
Capped PF: pros
- About ₹6,400 more cash in hand every month
- Useful if you have rent, EMIs or a family to support
- Your employer’s share also shrinks, so CTC is moved into gross pay
Capped PF: cons
- Your EPF grows much more slowly
- You lose a guaranteed, tax-free 8.25% return
- Not every employer allows it
If you already invest regularly, a higher EPF balance is a good thing: it is forced, tax-free saving. If you need cash today, a capped PF is a fair choice. Check with HR, because the option depends on company policy.
New vs old regime at 10 LPA
The old regime lets you claim HRA, 80C and 80D, but its rates are higher. At 10 LPA, the new regime wins in both common cases:
| Situation (old regime) | Old regime tax | New regime tax | Better choice |
|---|---|---|---|
| 80C ₹1.5 lakh + 80D ₹25,000, no rent | ₹52,718 | ₹0 | New |
| Same, plus HRA exemption of ₹1.9 lakh (rent ₹20,000/month, metro) | ₹13,198 | ₹0 | New |
So unless you have unusual deductions, stay in the new regime at 10 LPA. Read our new vs old tax regime guide for the break-even table, or run both in the income tax calculator.
In-hand salary for other CTCs (FY 2026-27)
Same assumptions (50% basic, PF on full basic, new regime, ₹2,500 professional tax):
| CTC | In-hand per month | Income tax a year | In-hand as % of CTC |
|---|---|---|---|
| ₹6 lakh | ₹42,589 | ₹0 | 85% |
| ₹8 lakh | ₹56,855 | ₹0 | 85% |
| ₹10 lakh | ₹71,121 | ₹0 | 85% |
| ₹12 lakh | ₹85,387 | ₹0 | 85% |
| ₹15 lakh | ₹1,00,299 | ₹77,832 | 80% |
| ₹18 lakh | ₹1,18,126 | ₹1,20,699 | 79% |
| ₹20 lakh | ₹1,29,330 | ₹1,57,435 | 78% |
| ₹25 lakh | ₹1,56,126 | ₹2,63,868 | 75% |
Notice how in-hand pay stays at 85% of CTC until ₹12 lakh, then starts to fall as income tax kicks in. See the full breakup in our 15 LPA in-hand salary guide.
How to budget ₹71,121 a month
A simple starting point is the 50/30/20 rule: half for needs, 30% for wants and 20% for savings.
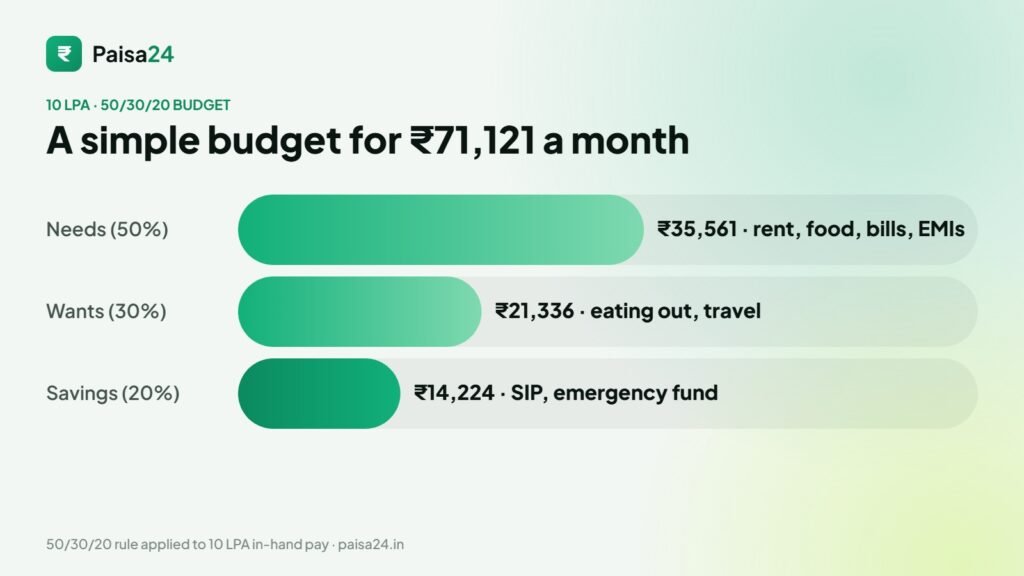
Saving ₹14,224 a month adds up fast. Invested in a diversified equity SIP at an assumed 12% a year, it could grow to about ₹33 lakh in 10 years and about ₹1.42 crore in 20 years. Also remember that your EPF quietly adds another ₹1.2 lakh a year on top. See what a ₹10,000 SIP becomes for more numbers.
Before you invest: Build an emergency fund of 3 to 6 months of expenses first, about ₹1 lakh to ₹2 lakh at this salary, and buy term and health insurance if your employer cover is small.
How to increase your take-home pay
- Pick the right regime early. Tell HR in April, so TDS is right from the first payslip.
- Ask about the PF basis. PF on ₹15,000 instead of full basic adds about ₹6,400 a month at 10 LPA.
- Use flexi-benefits. Meal cards, fuel, phone and internet reimbursements can cut tax at higher salaries.
- Ask for employer NPS. In the new regime, your employer’s NPS contribution of up to 14% of basic is tax-free.
- Negotiate fixed pay, not CTC. Variable pay and joining bonuses inflate CTC without raising your monthly cash.
Tip: When comparing job offers, compare fixed in-hand pay, not CTC. A 10 LPA offer with ₹1.5 lakh variable pay may pay less each month than a fully fixed 9 LPA offer.
How we calculated this: We used FY 2026-27 new regime slabs with the ₹75,000 standard deduction and the full rebate up to ₹12 lakh of taxable income, 4% cess, 50% basic, PF at 12% on both sides, gratuity at 4.81% of basic and professional tax of ₹2,500 a year. Your exact figure depends on your company’s structure, state and any variable pay.
Frequently asked questions
What is the in-hand salary for 10 LPA?
About ₹71,121 a month in the new regime with 50% basic and PF on full basic. With PF capped at ₹1,800 a month, it is about ₹77,521.
How much tax do I pay on 10 LPA?
Nothing in the new regime. Your taxable income is about ₹8.41 lakh after the ₹75,000 standard deduction, which is under ₹12 lakh, so the rebate makes tax zero.
Is 10 LPA in-hand salary the same in every city?
Almost. Only professional tax changes by state, up to ₹2,500 a year. In Delhi, Haryana and Uttar Pradesh there is none, so you get about ₹208 more a month.
Is the new or old regime better at 10 LPA?
The new regime. Even with ₹1.5 lakh of 80C, ₹25,000 of 80D and a ₹1.9 lakh HRA exemption, the old regime costs about ₹13,000 a year while the new regime costs nothing.
Why is my in-hand salary so much lower than my CTC?
Employer PF and gratuity are counted in CTC but never paid monthly, and your own PF and professional tax are deducted from gross pay. Together they take about 15% of a 10 LPA CTC.
What is 10 LPA per month before deductions?
₹10 lakh divided by 12 is ₹83,333 a month. After employer PF and gratuity, your gross monthly pay is about ₹76,329, and after your PF and professional tax you receive about ₹71,121.
Can I withdraw my PF if I need money?
Yes, partly. EPFO allows partial withdrawals for needs such as a home, medical treatment, education or marriage, subject to rules on years of service.
How much should I save on a 10 LPA salary?
A good target is at least 20% of take-home pay, about ₹14,000 a month, plus your EPF. Start with an emergency fund, then a monthly SIP.
Related guides and calculators
- 15 LPA in-hand salary: monthly take-home
- CTC vs in-hand salary explained
- Income tax slabs FY 2026-27
- How to claim HRA exemption
- Salary calculator: CTC to in-hand
Sources: Income Tax Department · EPFO · Ministry of Labour and Employment. Last checked 24 October 2026. Figures are estimates for guidance, not tax or financial advice. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.