RBI MPC December 2026: Will Home Loan EMIs Rise Again? What Economists Expect
RBI MPC December 2026 meets 2 to 4 December after the hike to 5.50%. See what economists expect and how much a ₹50 lakh home loan EMI could rise.
On this page 6 sections
The RBI MPC December 2026 meeting runs from 2 to 4 December, and several forecasters expect another repo rate hike. The repo rate stands at 5.50% after the RBI raised it by 25 basis points on 7 October. Nomura expects another 25 bps to 5.75%, while SBI Research has called for 50 bps. Nothing is decided until the RBI announces it. Here is what each outcome could mean for a ₹50 lakh, 20-year home loan.
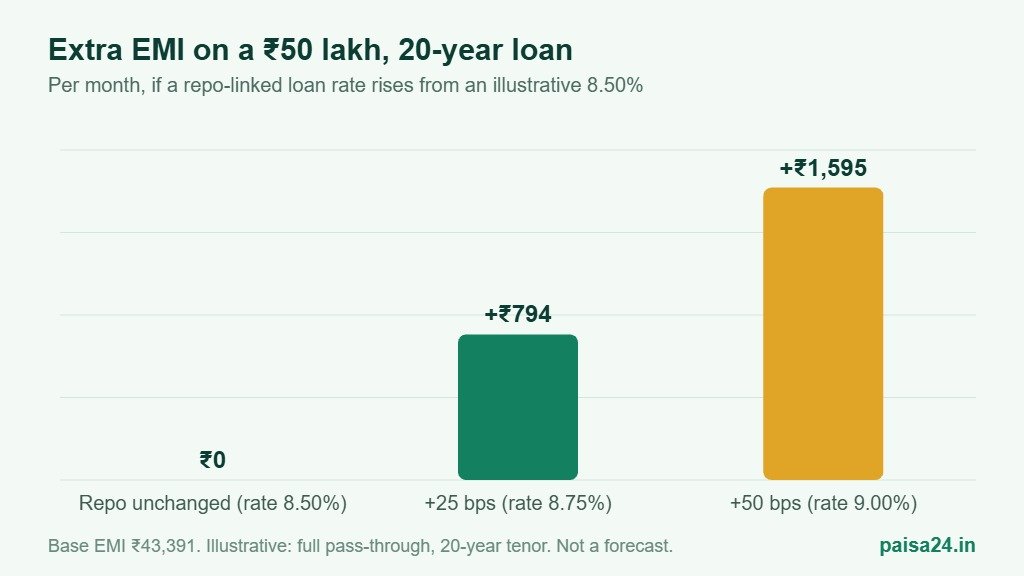
Quick answer: Each 25 bps rise in a repo-linked loan rate adds about ₹794 a month to the EMI on a ₹50 lakh, 20-year loan (8.50% to 8.75%). Over the full term, that is about ₹1.91 lakh in extra interest.
Key takeaways
- The MPC meets from 2 to 4 December 2026. The repo rate is 5.50% after the 7 October hike.
- Nomura expects +25 bps to 5.75% and then a long pause. SBI Research has called for +50 bps.
- Forecasts differ, and the RBI can still hold, hike by 25 bps or choose another mix.
- On a ₹50 lakh, 20-year loan, +25 bps adds about ₹794 a month and +50 bps adds about ₹1,595 a month.
- Only floating-rate loans linked to benchmarks like the repo rate move at reset. Fixed-rate loans do not change.
What economists expect from the RBI MPC December 2026 meeting
| Forecaster | Expected move | Repo rate after | Note |
|---|---|---|---|
| Nomura | +25 bps | 5.75% | Expects an extended pause after December; February stays open |
| SBI Research | +50 bps | 6.00% | Said on 22 October: either a plain 50 bps repo hike or 25 bps plus a 25 bps asymmetric widening of the LAF corridor |
| Poll of 53 economists | At least +25 bps (29 of 53) | 5.75% or higher | Poll reported by Outlook Money before the October meeting |
SBI Research also projects headline inflation at about 6% in the third quarter of FY2026-27, a key reason for its call. Forecasts can change with new data, so read them as scenarios, not outcomes.
How an RBI MPC December 2026 hike could change your ₹50 lakh home loan EMI
| Scenario | Repo rate | Loan rate (illustrative) | EMI | Change a month | Extra interest over 20 years |
|---|---|---|---|---|---|
| No change | 5.50% | 8.50% | ₹43,391 | — | — |
| +25 bps | 5.75% | 8.75% | ₹44,186 | +₹794 | ₹1.91 lakh |
| +50 bps | 6.00% | 9.00% | ₹44,986 | +₹1,595 | ₹3.83 lakh |
This assumes a repo-linked loan with full pass-through, 20 years remaining and no prepayment. Many lenders reset the rate on a fixed schedule, so a change may reach you after a lag. If your lender keeps the EMI unchanged, the tenor stretches instead: about 1 year longer after +25 bps and about 2 years 3 months longer after +50 bps.
Who is affected and who is not
- Repo-linked (EBLR) home loans: the rate rises at your next reset date.
- Older MCLR or base-rate loans: they change on their own reset schedule, usually with a lag.
- Fixed-rate loans: no change until the fixed period ends.
- Savers: deposit rates may rise too. See which banks raised FD rates after the October hike.
Watch out: Forecasts are not decisions. The RBI could hold the rate, hike by 25 bps or choose a different mix. We will update this article after the announcement.
What to do before the RBI MPC December 2026 decision
- Check your loan type and reset date in your sanction letter or loan statement.
- Decide between a higher EMI and a longer tenor. RBI guidance on floating-rate loans expects lenders to offer such a choice and to allow prepayment. Confirm what applies to your loan with your lender.
- Part-prepay if you have spare cash. Even a small lump sum reduces interest. Read whether to reduce EMI or tenure.
- Compare before you switch. Ask about processing fees and switching charges before moving to another lender or a fixed rate.
- Check your budget. Test a higher EMI against the 40% rule for EMI.
Frequently asked questions
When is the RBI MPC meeting in December 2026?
The Monetary Policy Committee meets from 2 to 4 December 2026. The decision is expected on the last day of the meeting.
What is the current repo rate?
The repo rate is 5.50% after the RBI raised it by 25 basis points on 7 October 2026.
Will home loan EMIs rise in December?
Only if the RBI raises rates and your lender passes it on. Repo-linked loans change at reset. Fixed-rate loans do not change.
How much will a 25 bps hike add to a ₹50 lakh EMI?
About ₹794 a month on a 20-year loan, if the rate rises from 8.50% to 8.75%.
Should I switch to a fixed-rate home loan now?
That depends on the cost and your plans. Ask your lender about switching charges and compare the fixed rate with your current rate before deciding. This is general information, not advice.
Related reading
- How the RBI repo rate hike to 5.50% changes your EMI
- EMI for ₹50 lakh home loan
- Salary required for a ₹50 lakh home loan
- FD rates after the RBI repo hike
Sources: Outlook Money · SBI Research via NewKerala · Nomura forecast via Lapaas Voice · PropNewz · RBI. Last updated 18 November 2026. EMI figures are our own calculations on an illustrative loan. How we research and fact-check.
This guide is for information only and isn’t financial advice. Rates, fees and rules change — always confirm on the official website before you decide. Read our disclaimer.